Most people retire on a mix of the State Pension, a workplace or personal pension, and savings such as ISAs. The State Pension alone gives a basic income, but it is unlikely to match what you earn while working. This guide covers how each part works, the 2026/27 rules and limits, and what the 28 October 2026 Budget changed, with every figure checked against GOV.UK and HMRC.
Key takeaways
- Full new State Pension: £241.30 a week in 2026/27 (GOV.UK). You need 10 qualifying years to get anything and usually 35 for the full amount.
- Expected rise to about £250.70 a week (£13,036 a year) from April 2027 under the triple lock (Which?).
- Workplace pensions: the legal minimum is 8% of qualifying earnings, with at least 3% from your employer (GOV.UK).
- Private pension access age rises from 55 to 57 on 6 April 2028 (HMRC).
- Annual allowance: £60,000 of pension contributions a year with tax relief, unchanged for 2027/28 in the Budget.
How does the UK pension system work?
The UK pension system has three layers: the State Pension from the government, workplace pensions through your employer, and personal pensions you arrange yourself. Most people end up with income from at least two of them.
| Pension type | Who pays in | What you get | Key 2026/27 figure |
|---|---|---|---|
| New State Pension | You, through National Insurance | A fixed weekly amount from State Pension age | £241.30 a week (full rate) |
| Workplace pension (defined contribution) | You, your employer and tax relief | A pot you can draw from 55 (57 from April 2028) | Minimum 8% total, 3% employer |
| Defined benefit (final salary) | Mainly your employer | A guaranteed income based on salary and service | Set by your scheme |
| Personal pension or SIPP | You (plus tax relief) | A pot you invest and control | Counts towards the £60,000 annual allowance |
The State Pension
The new State Pension is paid to people who reached State Pension age on or after 6 April 2016. GOV.UK says you need 10 qualifying years on your National Insurance record to get any, and 35 qualifying years for the full £241.30 a week if your record started after April 2016. People who were contracted out before 2016 may need more. If you reached State Pension age before April 2016, you get the older basic State Pension instead.
Check your State Pension forecast to see what you're on track for and whether you have gaps you could fill.
Workplace pensions
Most employers must automatically enrol eligible staff into a workplace pension. Under the minimum rules, contributions are based on your earnings between £6,240 and £50,270 a year, with 5% from you (including tax relief) and 3% from your employer. Many employers pay more if you do, so it's worth asking whether yours matches extra contributions.
There are two kinds: defined contribution, where your pot depends on what's paid in and how investments perform, and defined benefit, which pays a set income linked to your salary and years of service.
Personal pensions and SIPPs
A personal pension, including a self-invested personal pension (SIPP), is one you set up yourself. It suits the self-employed, people who want to top up a workplace pension, or anyone who wants more control over investments. Contributions get tax relief, within the annual allowance.
Take Action: check your State Pension forecast and log in to each workplace pension you have, so you know your starting point.
Will the State Pension be taxed?
Yes, the State Pension is taxable income, but it's paid without tax taken off. In 2026/27 the full new State Pension (£12,547.60 a year) is just below the £12,570 Personal Allowance. From April 2027 it's expected to rise above it, while HMRC's Budget rates annex keeps the Personal Allowance at £12,570.
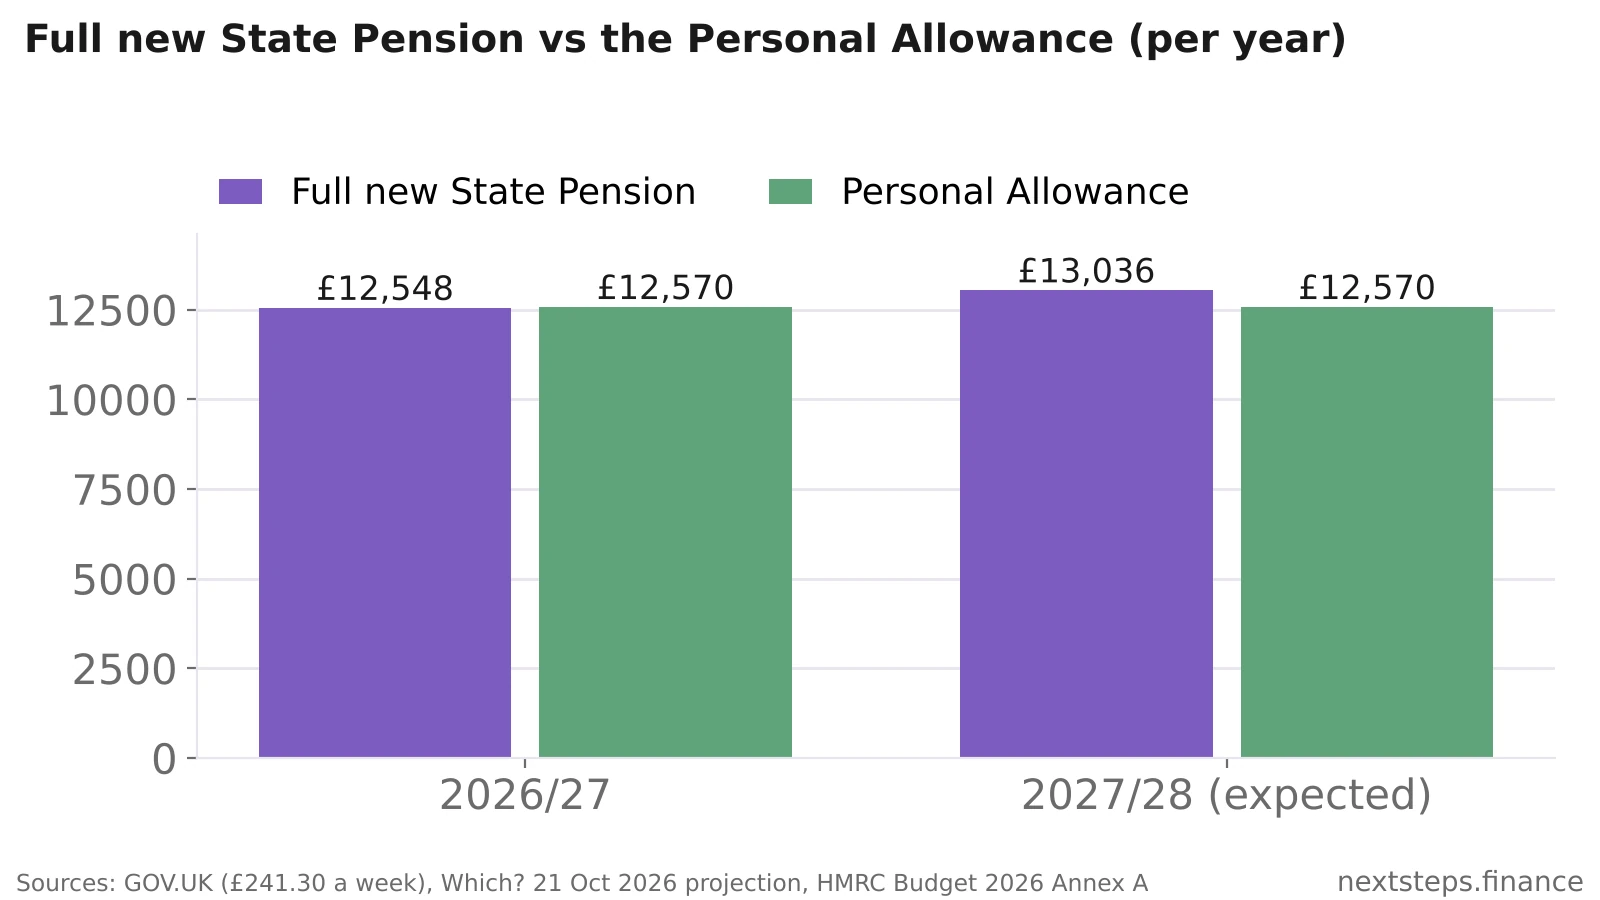
To stop pensioners being chased for small tax bills, the Budget on 28 October 2026 created a Pensions Tax Allowance for 2027/28 to 2029/30. HMRC says pensioners with total income up to the full new State Pension won't have to pay those small amounts. The 2027/28 eligibility threshold is £13,037 of income, and the allowance is withdrawn at £1 for every £3 above that, disappearing at £13,319. Our Budget 2026 guide explains the other changes, and our State Pension rise guide has the expected new rates.
When can you retire and access your pension?
You can stop working whenever you like, but the State Pension and private pensions each have their own minimum ages.
- State Pension age is currently 66 and is rising gradually to 67 between 2026 and 2028 for people born on or after April 1960 (Which?). Check your State Pension age on GOV.UK, as it depends on your date of birth.
- Private and workplace pensions can usually be accessed from 55. HMRC confirms the normal minimum pension age rises to 57 from 6 April 2028.
When you access a defined contribution pot you can usually take up to 25% tax-free, within the £268,275 Lump Sum Allowance. The rest is taxed as income when you take it, so large withdrawals in one tax year can push you into a higher tax band.
| Age milestone | What it means |
|---|---|
| 50 | You can book a free Pension Wise appointment |
| 55 (57 from 6 April 2028) | Earliest normal age to access private pensions |
| 60 | Lifetime ISA money can be withdrawn without a charge |
| 66, rising to 67 (2026-2028) | State Pension age |
Take Action: if you're planning to retire before State Pension age, work out how you'll cover the gap from savings or your pension.
How much do you need to retire?
There's no single number. What you need depends on the lifestyle you want, whether you'll still have housing costs, and how much State Pension you'll get. A good starting point is your current spending, minus costs that stop at retirement (commuting, mortgage payments, pension contributions), plus costs that may rise (travel, hobbies, care).
- List your expected monthly costs in retirement. Our UK Budget Planner is a quick way to do this.
- Subtract your expected State Pension from your forecast.
- The gap is what your pensions and savings need to cover each year, for possibly 25 years or more.
- Run the numbers with the MoneyHelper pension calculator to see whether your contributions are on track.
Take Action: if there's a gap, small increases now (even 1% of salary, especially if your employer matches it) make a big difference over decades.
How can you boost your pension?
The most effective ways to grow your pension are to pay in more, make the most of employer contributions and tax relief, and keep track of old pots.
- Get the full employer match. Free money from your employer is the best return available.
- Use tax relief. Contributions get relief at your marginal rate, within the £60,000 annual allowance (or 100% of your earnings if lower). If you've already flexibly accessed a pension, the Money Purchase Annual Allowance of £10,000 applies instead.
- Review how your pension is invested. Many people never change from the default fund. If you're decades from retirement, check the risk level suits you.
- Find lost pensions. Use the government's Pension Tracing Service to find contact details for old schemes, then consider whether combining them makes sense. Check for exit fees or valuable guarantees before transferring.
Take Action: log in to your pension provider and check your contribution rate and fund choice this month.
What about ISAs and other retirement savings?
ISAs are a flexible partner to your pension. You can pay in up to £20,000 a year, there's no tax on growth or withdrawals, and you can access the money at any age. Unlike a pension, there's no tax relief on the way in.
- Stocks and shares ISAs suit long-term investing alongside a pension. Platforms such as InvestEngine offer low-cost ETF portfolios with no platform fee on DIY accounts (ETF costs apply). Capital at risk - the value of investments can go down as well as up.
- Lifetime ISAs let 18 to 39 year olds save up to £4,000 a year with a 25% government bonus (up to £1,000 a year), usable for a first home or from age 60 (GOV.UK). Other withdrawals carry a 25% charge. The Budget confirmed the LISA will close to new savers when a home-only First Time Buyer ISA launches in April 2029, but existing accounts can carry on.
- Cash ISAs are useful for money you'll need in the first few years of retirement. The cash ISA limit stays at £20,000 for everyone after the 2026 Budget scrapped the planned cut.
See our ISA and LISA guide and the ISA allowance rules for 2026/27.
Should you get pension advice?
Free guidance is available to everyone over 50 with a defined contribution pension, and regulated advice is worth considering for big decisions.
- Pension Wise from MoneyHelper offers free, impartial guidance if you're 50 or over with a UK defined contribution pension, on the options for taking your money (MoneyHelper).
- A regulated financial adviser can help with larger pots, defined benefit transfers, annuity versus drawdown decisions, and inheritance planning. From 6 April 2027, unused pension pots will count towards your estate for inheritance tax, so it's worth reviewing your will and pension nominations.
If you'd like a second pair of eyes on your overall plan, see our personal finance review.
Frequently asked questions
How much is the full State Pension in 2026/27?
The full new State Pension is £241.30 a week in the 2026/27 tax year, or about £12,548 a year, according to GOV.UK. You need 35 qualifying years of National Insurance for the full amount and at least 10 years to get anything. It's expected to rise to about £250.70 a week from April 2027.
What age can I retire in the UK?
There's no fixed retirement age in the UK, so you can stop work whenever you can afford to. State Pension age is currently 66 and is rising to 67 between 2026 and 2028. You can usually access private and workplace pensions from 55, rising to 57 from 6 April 2028.
How many years of National Insurance do I need for a full State Pension?
You usually need 35 qualifying years of National Insurance contributions or credits to get the full new State Pension, and at least 10 years to get any. If you were contracted out before April 2016 you may need more. Check your forecast on GOV.UK to see any gaps.
Can I take 25% of my pension tax-free?
Yes. You can usually take up to 25% of a defined contribution pension tax-free from age 55 (57 from 6 April 2028). The total tax-free cash across all your pensions is capped by the Lump Sum Allowance of £268,275. The rest is taxed as income when you withdraw it.
Is the State Pension enough to live on?
For most people, no. The full new State Pension of £241.30 a week (2026/27) covers basic costs for some, but it's a safety net rather than a full income. Most people need workplace or personal pensions and savings to keep a similar lifestyle. Pension Wise and calculators can help you plan.
What happens to my pension when I die?
Defined contribution pensions can usually be passed to the people you nominate. From 6 April 2027, unused pension funds and death benefits will count towards your estate for inheritance tax. The Budget on 28 October 2026 also removed the two-year rule for pension death benefits paid from that date. Keep your nominations up to date.
Next steps
Retirement planning is worth doing at any age, and the earlier you start, the more compound growth works for you.
- Check your State Pension forecast and fill any National Insurance gaps if it's worth it.
- Log in to every pension you have and note the value, contribution rate and fund.
- Increase contributions if there's a gap, starting with any employer match.
- Use ISAs alongside your pension for flexible savings.
- Book Pension Wise at 50, and get regulated advice for big decisions.