Your ISA allowance is the most valuable tax break most people have. Everything inside an ISA grows free of income tax and capital gains tax, and you never have to declare it. This guide covers the limits for the 2026/27 tax year (6 April 2026 to 5 April 2027), the rules that trip people up, and what the 28 October 2026 Budget changed.
Key takeaways
- £20,000 total ISA allowance for 2026/27. It doesn't roll over, so unused allowance is lost after 5 April 2027.
- You can pay into several ISAs of the same type in one tax year, e.g. two cash ISAs. That has been allowed since April 2024.
- Lifetime ISA: up to £4,000 a year (part of the £20,000), with a 25% government bonus worth up to £1,000. Open it before you turn 40.
- Junior ISA: £9,000 per child per year, on top of your own allowance.
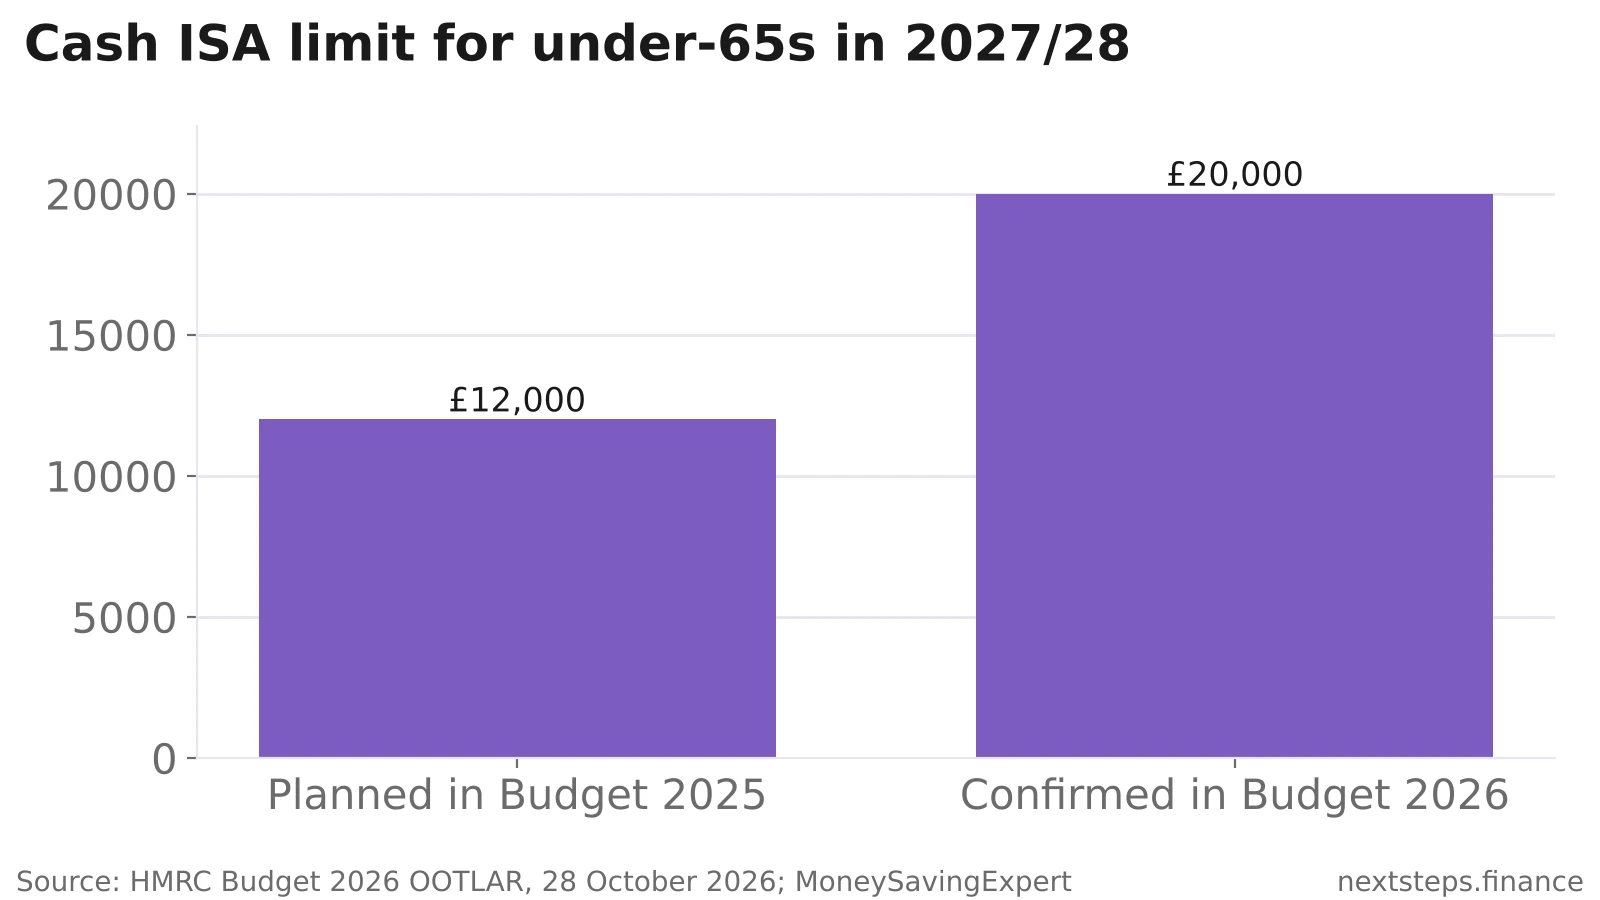
- The cash ISA cut is scrapped: the Budget on 28 October 2026 kept the cash ISA limit at £20,000 for all savers aged 18+ from April 2027.
What is the ISA allowance for 2026/27?
£20,000 per adult, for the tax year 6 April 2026 to 5 April 2027. It covers everything you pay into adult ISAs in that year:
| ISA type | 2026/27 limit | Counts towards £20,000? |
|---|---|---|
| Cash ISA | Up to £20,000 | Yes |
| Stocks & Shares ISA | Up to £20,000 | Yes |
| Innovative Finance ISA | Up to £20,000 | Yes |
| Lifetime ISA | Up to £4,000 | Yes |
| Junior ISA (per child) | £9,000 | No, separate allowance |
Growth, interest and dividends inside an ISA don't count towards the allowance. Only the money you pay in does. Transfers of previous years' ISA money between providers don't use any allowance either.
Take Action: Setting up £1,667 a month uses the full £20,000 by the end of the tax year. Any regular amount you can afford beats waiting until March.
Is the cash ISA limit changing in April 2027?
No. The 2025 Budget planned to cap cash ISA payments at £12,000 a year for under-65s from April 2027, but the Budget on 28 October 2026 scrapped that plan. HMRC's Budget overview says the government "will retain the cash ISA limit at £20,000 for all savers over 18 years old from April 2027".
The Budget also confirmed that the Lifetime ISA will be replaced by a First Time Buyer ISA for new savers from April 2029, and that the LISA withdrawal charge for homes above the £450,000 cap falls from 25% to 20% from 29 October 2026. A new Starter ISA incentive for first-time investors is also planned. Our Budget 2026 guide covers all the changes.
What it means for you: there's no need to rush cash into ISAs before April 2027 because of a cap. But tax on savings interest outside ISAs rises to 24%, 44% and 49% from 6 April 2027, so sheltering taxable savings in a cash ISA is worth more than before.
Cash ISA or stocks & shares ISA?
| Cash ISA | Stocks & Shares ISA | |
|---|---|---|
| Returns | Fixed or variable interest | Investment growth and dividends, not guaranteed |
| Risk | Capital safe; FSCS protected up to £120,000 per bank | Capital at risk; value can fall |
| Best for | Emergency fund, goals within ~5 years | Goals 5+ years away |
| Access | Easy-access or fixed term | Sell any time, but value varies |
Many people use both: an emergency fund of 3-6 months' spending in cash, and the rest invested. For the investing side, low-cost platforms like InvestEngine (ETF portfolios, £0 platform fee for DIY) and Trading 212 (shares and ETFs, £0 commission) keep costs down. Capital at risk: the value of investments can go down as well as up. Compare platforms in our guide to the best stocks and shares ISAs, and cash rates in best savings accounts.
How does the Lifetime ISA work?
The Lifetime ISA (LISA) is for a first home or retirement:
- Pay in up to £4,000 a year, which counts towards your £20,000.
- The government adds a 25% bonus, up to £1,000 a year.
- You must be 18-39 to open one, and you can pay in until you're 50.
- Use it penalty-free to buy your first home (price cap applies) or after age 60.
- Withdraw for anything else and you pay a 25% charge on the amount withdrawn. That means you get back less than you put in.
A LISA is excellent if you're saving for a first home, but think carefully before using it for retirement if you have a workplace pension with employer contributions.
What are the ISA rules most people get wrong?
- "I can only pay into one cash ISA a year." Not any more. Since April 2024 you can pay into multiple ISAs of the same type in a tax year, as long as the total stays within £20,000.
- Withdrawing to switch providers. Always use the new provider's ISA transfer process. If you withdraw and pay back in, you lose the tax wrapper and use up allowance.
- Going over £20,000. HMRC will remove the excess and any tax-free growth on it.
- Assuming you can replace withdrawals. You can only do this with a flexible ISA, and within the same tax year. Check whether yours is flexible.
- Forgetting the deadline. Allowance left at 5 April 2027 is lost for good.
How to make the most of your ISA allowance
- Start early in the tax year. Money invested in April has nearly a full extra year to grow tax-free.
- Bed and ISA: if you hold investments outside an ISA, many platforms will sell and rebuy them inside your ISA in one step. Capital gains tax may apply on the sale.
- Use your partner's allowance too. Each adult gets £20,000, so a couple can shelter £40,000 a year.
- Open a Junior ISA for children. £9,000 a year, locked until they turn 18.
- Shelter taxable savings first. From 6 April 2027, interest outside an ISA is taxed at 24% for basic-rate taxpayers (above the Personal Savings Allowance).
Related guides
FAQ
What is the ISA allowance for 2026/27?
The ISA allowance for the 2026/27 tax year is £20,000 per adult, running from 6 April 2026 to 5 April 2027. You can split it across cash, stocks & shares, innovative finance and Lifetime ISAs, with Lifetime ISAs capped at £4,000 of the total. Junior ISAs have a separate £9,000 limit per child.
Can I pay into two cash ISAs in the same tax year?
Yes. Since 6 April 2024 you can pay into more than one ISA of the same type in a tax year, including two or more cash ISAs, as long as your total payments across all adult ISAs stay within the £20,000 allowance.
Is the cash ISA allowance being cut?
No. The planned cut to £12,000 for under-65s from April 2027 was scrapped in the Budget on 28 October 2026. The cash ISA limit stays at £20,000 a year for all savers aged 18 and over, and the overall £20,000 ISA allowance is unchanged. Junior ISAs stay at £9,000 per child.
What happens if I don't use my ISA allowance?
It's lost. Any part of your £20,000 allowance unused by 5 April 2027 can't be carried forward to the next tax year. The money already in your ISAs stays tax-free, but you start the new tax year with a fresh £20,000 allowance only.
How does the Lifetime ISA bonus work?
The government adds 25% to what you pay into a Lifetime ISA, up to £1,000 a year on £4,000 of contributions. You must open it before 40 and can pay in until 50. Withdrawing for anything other than a first home or after 60 triggers a 25% charge.
The information in this article is for educational purposes only and does not constitute financial or tax advice. Tax rules can change and their effect depends on your circumstances. Capital at risk with stocks and shares ISAs.
Sources: GOV.UK: Individual Savings Accounts, GOV.UK: Lifetime ISA, GOV.UK: Junior ISAs, Moneysupermarket: ISA changes 2027.