A budget is simply a plan for where your money goes each month, made before you spend it rather than after. This guide covers how to create a budget in the UK step by step, the budgeting methods that work, the tools worth using and how to stick with it.
Key takeaways
- Start with take-home pay, not salary. Budget from what actually lands in your account after tax, National Insurance, pension and student loan deductions.
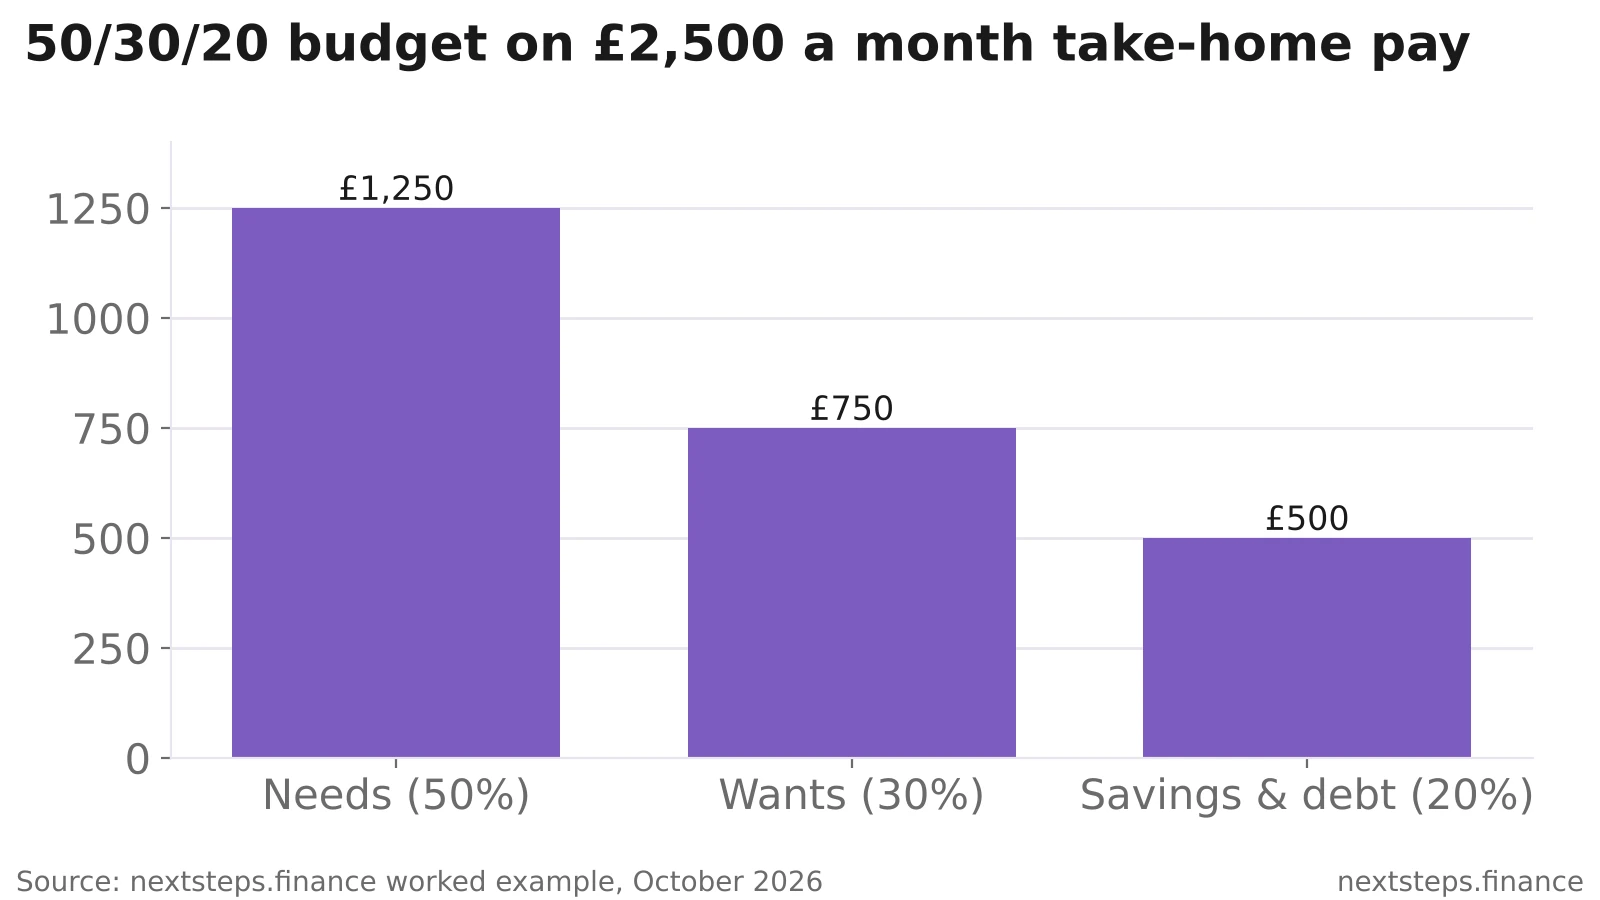
- The 50/30/20 rule splits £2,500 of monthly take-home pay into £1,250 for needs, £750 for wants and £500 for savings and debt.
- UK households spent an average of £676.60 a week in the year to March 2025, up 9% on the year before, according to the ONS.
- Unsecured debt averaged £4,511 per UK adult in May 2026, according to The Money Charity, which is why a budget that includes debt repayment matters.
- Free tools are enough for most people: a spreadsheet, your bank's app or the free version of a budgeting app.
What is budgeting and why does it matter?
Budgeting means deciding in advance how you'll split your income between bills, everyday spending, savings and debt. It turns "where did it all go?" into a plan you control.
A budget helps you avoid borrowing for things you could have planned for, build an emergency fund and work towards bigger goals. It matters more when prices are rising: the ONS found average household spending rose by £53.30 a week (9%) in the year to March 2025, and £35.10 (5%) after inflation.
Debt is the other reason. The Money Charity's July 2026 statistics put average unsecured debt at £8,772 per household and £4,511 per adult in May 2026. Including mortgages, the average household owed £67,802.
How do I create a budget in the UK?
Create a budget in three steps: work out your monthly take-home income, list all your outgoings, then subtract one from the other and decide what to do with what's left. Use your last three months of bank statements so the numbers are real, not guesses.
- Calculate your monthly income. Use take-home pay after tax and deductions, plus any benefits, rental income or side income. If your income varies, use your lowest typical month.
- List all your expenses. Sort them into three groups:
- Do the maths. Subtract expenses from income. If there's money left, give it a job: savings, extra debt repayments or a goal. If you're spending more than you earn, cut discretionary spending first, then look at bills you can switch.
- Add irregular costs. Car insurance, MOT, Christmas, birthdays and annual subscriptions catch people out. Add up the yearly total, divide by 12 and set that aside each month.
Take Action: Download your last three months of bank statements and sort them into categories using the UK Budget Planner, a ready-made Google Sheet built for UK pay, tax and bills. MoneyHelper's free budget planner is a good online alternative.
What is the best budgeting method UK?
The best budgeting method is the one you'll keep using. The 50/30/20 rule is the easiest place to start; zero-based budgeting gives the most control; and "pay yourself first" suits people who find saving hard.
| Method | How it works | Best for | Effort |
|---|---|---|---|
| 50/30/20 rule | 50% needs, 30% wants, 20% savings and debt | Beginners | Low |
| Zero-based budgeting | Every pound gets a job until income minus plan = £0 | Tight budgets, paying off debt | High |
| Envelope (pots) method | Fixed amount per category, stop when it's empty | Overspenders | Medium |
| Pay yourself first | Save a set amount on payday, spend the rest freely | People who struggle to save | Low |
| Anti-budget | Cover bills and savings, ignore the detail | Disciplined savers | Very low |
The 50/30/20 rule
The 50/30/20 rule divides your take-home pay into three buckets: 50% for needs (housing, bills, groceries, minimum debt payments), 30% for wants and 20% for savings and extra debt payments.
In high-rent areas, needs can easily take more than 50%. If so, adjust the split (for example 60/20/20) rather than abandoning the method.
Zero-based budgeting
Zero-based budgeting means assigning every pound of income a purpose until nothing is unallocated. It doesn't mean spending everything; savings and debt repayments are allocations too.
The envelope method
The envelope method gives each spending category a fixed amount, and when it's gone, it's gone. Today most people use savings pots in apps such as Monzo or Starling instead of cash envelopes.
Pay yourself first
Pay yourself first means moving a set amount to savings as soon as you're paid, then living on the rest. A standing order on payday makes it automatic.
How to stick to a budget UK
You stick to a budget by making it realistic, automating the important parts and reviewing it every month. Most budgets fail because they're too strict, not because people lack willpower.
Start with realistic numbers
Cut gradually. Reducing a category by 10% a month is easier to sustain than halving it overnight.
Automate savings and bills
Set up standing orders and direct debits for the day after payday. Money that moves automatically doesn't need willpower.
Build in a buffer
Add a "miscellaneous" line of £50 to £100 a month for the things you'll forget, such as a gift, a prescription or a parking fine.
Use a cooling-off rule
Wait 24 hours before buying anything over £50, and a week for anything over £200. It stops most impulse purchases.
Review monthly
Compare what you planned with what you spent, and adjust the categories to match reality rather than fighting it.
Budgeting tools and apps for UK users
The right tool is the one you'll actually open. Your options are a spreadsheet, your bank's built-in tools, or a dedicated budgeting app that pulls in all your accounts through Open Banking.
| Tool | Cost | Pros | Cons |
|---|---|---|---|
| Spreadsheet (UK Budget Planner) | Free | Full control, no bank access | Manual updates |
| Bank app (Monzo, Starling and others) | Free | Real-time, built-in pots | Only sees that bank |
| Emma budgeting app | Free; paid from £4.99 a month | All accounts in one place | Custom categories need Pro (£9.99 a month) |
| Snoop | Free; Snoop Plus £4.99 a month | Flags bill rises and unused subscriptions | Advanced budgeting needs Plus |
| Plum | Free; paid from £3.99 a month | Saves for you automatically | Full spend tracker needs Boost (£7.99 a month) |
Prices were checked against each provider's help centre or App Store listing on 27 October 2026. For a full comparison, read our guide to the best budgeting apps UK. Budgeting apps connect through Open Banking, which gives read-only access, and you can check any firm on the FCA register.
Take Action: Choose one method and one tool this week, and set up your first budget using real figures from your statements, even if it isn't perfect.
Common budgeting mistakes to avoid
The most common budgeting mistakes are forgetting irregular costs, being too strict and not tracking small spending.
- Forgetting irregular expenses. Annual bills like car insurance can wreck a month's budget. Defaqto data reported by Insurance Edge shows quoted car insurance premiums at the end of September 2026 were 2.7% higher than a year earlier, so check your renewal price and shop around.
- Being too restrictive. If the budget feels like a punishment, you'll drop it. Leave room for things you enjoy.
- Not tracking small spends. Coffees and meal deals add up. Track everything for one month to see the real picture.
- Leaving out your partner. If you share costs, agree the budget together.
Building your emergency fund through budgeting
Your first budgeting goal should usually be an emergency fund, because it stops a surprise bill becoming debt. Start with £1,000, then build towards three to six months of essential spending.
If your essential costs are £2,000 a month, that's a target of £6,000 to £12,000. Saving it in an easy-access account keeps it available and earning interest. Automatic saving apps such as Plum can help if you find it hard to put money aside, but check how each pocket is protected: Plum's e-money Primary Pocket isn't FSCS protected, and its investment pockets carry risk (capital at risk). Read our full emergency fund guide for where to keep it.
Budgeting for different life stages
Your budget priorities change as your life does.
- Students and young workers: focus on habits and avoiding expensive debt. Even £50 a month saved builds a buffer.
- Families with young children: childcare is often the biggest cost. Coram's Childcare Survey 2026 found families in England who aren't eligible for funded hours pay an average of £189 a week for a part-time nursery place for a child under two, while Coram reports that the cost of a full-time (50-hour) place in England has fallen by 39% on 2025 as funded hours have expanded. Check your entitlement to Tax-Free Childcare.
- Pre-retirement: prioritise pension contributions and clearing debts before you stop working.
- Retirement: budget around a fixed income and plan for rising costs over time.
Budgeting and debt management
If you have debt, your budget should list every balance, interest rate and minimum payment, then put spare money towards one debt at a time.
The avalanche method pays off the highest interest rate first and costs least overall. The snowball method clears the smallest balance first and gives quicker wins. Both work if you stick with them. Even an extra £25 a month can shorten the time it takes to clear a credit card.
If repayments feel unmanageable, free, confidential help is available from StepChange and National Debtline. Read our guide on how to get out of debt for more.
Frequently asked questions
How much should I budget for groceries in the UK?
Base your grocery budget on what you actually spent over the last three months, then trim 5-10%. Food costs vary widely by household size and area. The ONS found UK households increased spending on food and non-alcoholic drinks by £3.20 a week (5%) in the year to March 2025, so review this category regularly.
What is the 50/30/20 rule UK?
The 50/30/20 rule splits your monthly take-home pay into 50% for needs such as rent, bills and groceries, 30% for wants and 20% for savings and extra debt payments. On £2,500 a month take-home, that's £1,250, £750 and £500. Adjust the split if your housing costs are high.
How do I budget with irregular income?
Budget from your lowest typical month and cover essentials first. In better months, put the extra into a buffer account, then pay yourself a steady "salary" from it. If you're self-employed, set aside money for tax and National Insurance on every payment you receive so your Self Assessment bill isn't a shock.
Should I include pension contributions in my budget?
Yes. If your pension comes out of your pay through a workplace scheme, it's already taken before your take-home pay, so budget from the net figure. If you pay into a personal pension yourself, treat it as a fixed monthly cost. Employer contributions are effectively free money, so don't opt out to balance a budget.
What is the best free budgeting app UK?
Popular free budgeting apps in the UK include Emma and Snoop, which connect to your bank accounts through Open Banking and categorise your spending. Snoop's free version also flags bill rises and unused subscriptions. Your own bank's app may offer free spending insights and savings pots, too.
How often should I review my budget?
Review your budget every month for the first three months, comparing what you planned with what you actually spent. After that, a monthly ten-minute check is usually enough, with a bigger review when your pay, rent, bills or household changes.
The bottom line
The best budget is a simple one you'll keep using. Start by tracking one month of spending, pick a method like 50/30/20, automate your savings on payday and review it monthly. If you'd like a qualified second pair of eyes on your budget, book a personal finance review.
Take Action: Open your banking app now, find your three biggest spending categories from last month, and pick one to reduce by 10% next month.
The information in this article is for educational purposes only and does not constitute financial advice.