Student finance in England covers your tuition fees and part of your living costs, and you only repay it once you earn over a set threshold. The 2026/27 figures below are from GOV.UK, checked on 22 October 2026. There's also a big change coming: courses starting from 1 January 2027 move to the new Lifelong Learning Entitlement, with applications opening from the end of October 2026.
Key takeaways
- The Tuition Fee Loan for full-time undergraduates in England is up to £9,790 in 2026/27 (up from £9,535), or £11,750 for accelerated degrees.
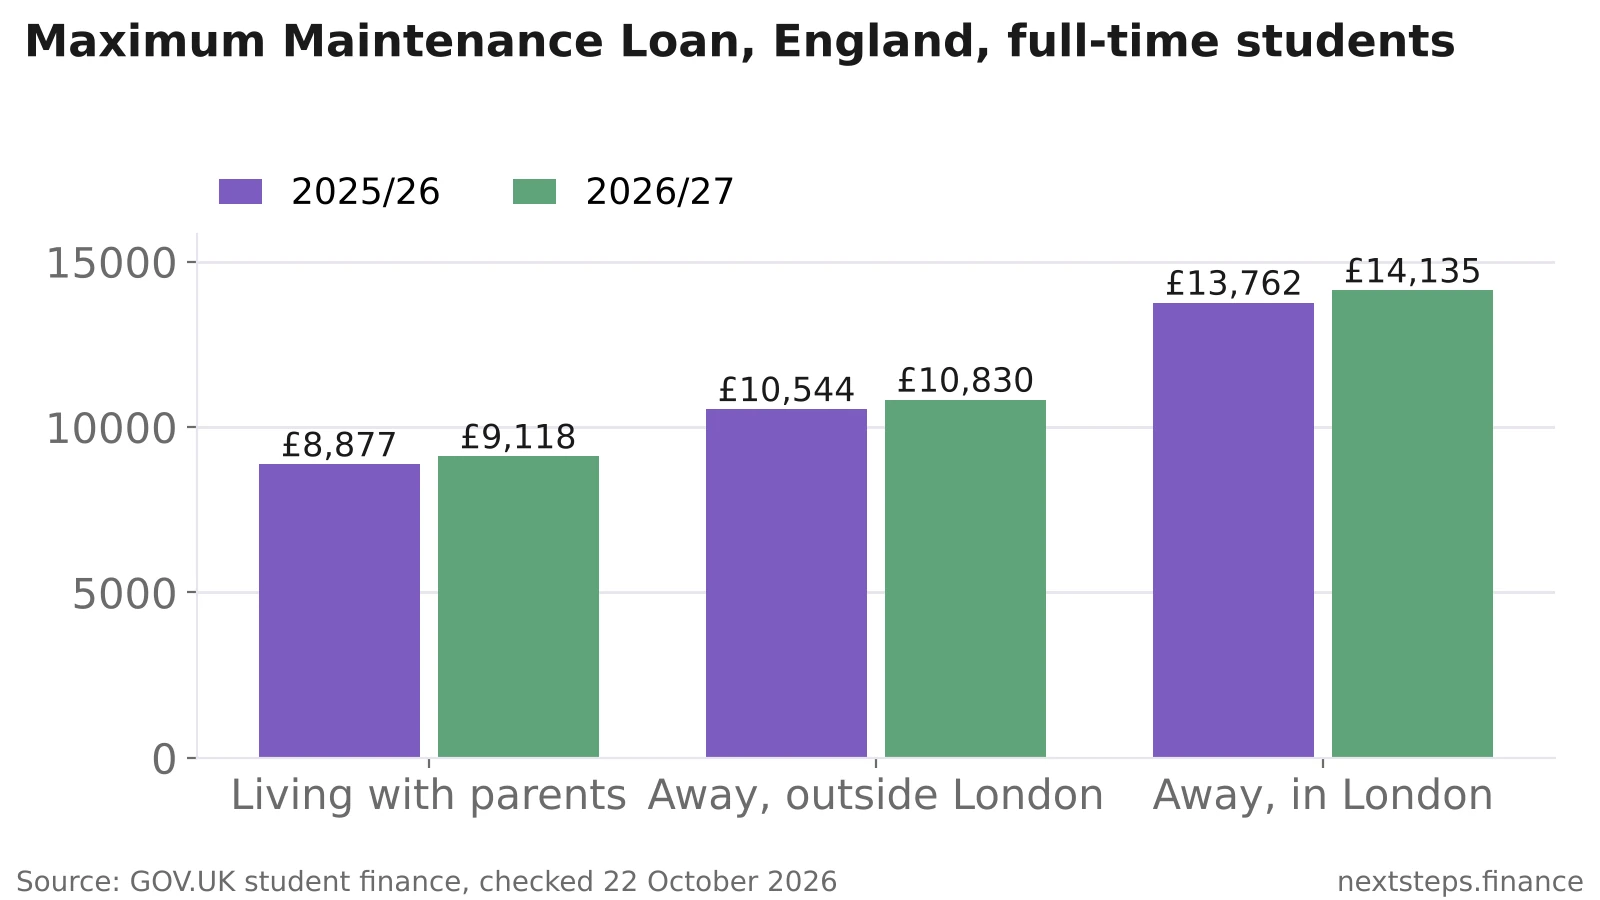
- The maximum Maintenance Loan is £9,118 living with parents, £10,830 away from home outside London and £14,135 in London.
- Plan 5 borrowers repay 9% of income above £25,000, and the interest rate is currently 4.1%.
- A student borrowing the maximum away from home outside London for three years would borrow about £62,000 before interest.
- Courses starting on or after 1 January 2027 use the Lifelong Learning Entitlement, with a total tuition loan of up to £39,160.
How does student finance work in the UK?
Student finance in England is a government loan that pays your tuition fees directly to your university and gives you a Maintenance Loan for living costs. You repay a share of your income above a threshold, not a fixed monthly amount.
Tuition Fee Loan: covers your course fees, up to £9,790 a year for most full-time undergraduate courses in 2026/27. It doesn't depend on household income.
Maintenance Loan: helps with rent, food and other living costs. How much you get depends on your household income and where you live while studying. The full amounts go to students from lower-income households.
| Where you live while studying | Max Maintenance Loan 2025/26 | Max Maintenance Loan 2026/27 |
|---|---|---|
| With your parents | £8,877 | £9,118 |
| Away from home, outside London | £10,544 | £10,830 |
| Away from home, in London | £13,762 | £14,135 |
| Year of a UK course studying abroad | £12,076 | £12,403 |
| Aged 60 or over on the first day of your course | £4,461 | £4,582 |
These figures are for England. Students from Scotland, Wales and Northern Ireland apply to SAAS, Student Finance Wales or Student Finance NI, which have different amounts.
Take Action: Use the government's student finance calculator to estimate your Maintenance Loan based on your household income.
How much is a degree going to cost?
The headline cost of a three-year degree in England is the fees plus whatever you borrow for living costs. At the 2026/27 maximums, that's about £29,370 in tuition fees plus up to £32,490 in Maintenance Loans if you live away from home outside London: roughly £62,000 in total before interest.
That figure overstates what most people repay, because repayments depend on your income, not your balance (see below). It also understates the real cost of university. Maintenance Loans rarely cover everything, especially in London, so many students rely on part-time work or family help. Building a simple term-time budget early helps a lot. Our free UK Budget Planner works well for this.
When do you start paying back a student loan?
On Plan 5, which covers undergraduate courses in England starting from August 2023, you start repaying the April after you finish your course, and only if you earn over £25,000 a year. You repay 9% of everything above that.
For example, on a salary of £35,000 you'd repay 9% of £10,000: £900 a year, or about £75 a month. It's taken through PAYE with your tax, so most employees never need to arrange payments themselves.
Other loan plans have different thresholds. You can check which plan you're on in your online student loan account (GOV.UK):
| Plan | Repayment threshold | You repay | Written off after |
|---|---|---|---|
| Plan 1 | £26,900 | 9% above threshold | 25 years (loans from Sept 2006) |
| Plan 2 | £29,385 | 9% above threshold | 30 years |
| Plan 4 | £33,795 | 9% above threshold | 30 years |
| Plan 5 | £25,000 | 9% above threshold | 40 years |
| Postgraduate Loan | £21,000 | 6% above threshold | 30 years |
Write-off periods are from the April you were first due to repay (GOV.UK).
What is the interest rate on student loans?
Plan 5 student loans currently charge 4.1% interest, the same as Plans 1 and 4. Postgraduate Loans charge 6%. Interest is added from your first payment, so your balance grows while you study.
Plan 2 works differently. While you're studying, the rate is RPI plus 3%, capped at 6%. After you leave, it depends on your income: 4.1% if you earn £29,385 or less, rising on a sliding scale to 6% at £52,885 or more.
Because repayments depend on what you earn, not what you owe, two graduates with the same balance can repay very different totals. Over a 40-year Plan 5 term, many middle earners will repay their loan in full, while lower earners may have some written off. Our student loans guide looks at whether making overpayments is worth it.
Take Action: Before you overpay a student loan, compare it with your other options. Paying off higher-interest debt or building an emergency fund usually comes first.
What is the Lifelong Learning Entitlement?
The Lifelong Learning Entitlement (LLE) replaces the current system for courses starting on or after 1 January 2027. It gives you a total tuition loan entitlement of up to £39,160, about four years of full-time study (or 480 credits), to use across your working life (GOV.UK).
You'll be able to use it for full degrees or shorter modules, which suits people retraining later in life. Repayments start once you earn over £25,000 a year, any balance is written off 40 years after the April you were first due to repay, and the interest rate is currently 4.1%. Applications open from the end of October 2026.
If you're starting a course in September 2026 or earlier, you stay on the current system.
Student grants and bursaries you don't have to repay
Grants and bursaries don't need to be repaid, so it's worth checking every one you might qualify for. The main sources are:
- Extra help from Student Finance England, such as the Childcare Grant, Parents' Learning Allowance, Adult Dependants' Grant and Disabled Students' Allowance (GOV.UK)
- NHS bursaries and grants for some healthcare courses
- University bursaries and scholarships, which vary widely between institutions and are often aimed at students from lower-income households
- Charities, professional bodies and employers offering subject-specific funding
Many students miss out because they don't look or miss deadlines. Check each university's funding page as soon as you have a shortlist.
Take Action: Make a list of every bursary and grant for your course and shortlisted universities, with deadlines and eligibility rules.
Alternatives to university that avoid student debt
Apprenticeships, employer-sponsored study and professional qualifications can get you qualified without a student loan. They're worth comparing seriously before you commit.
Apprenticeships now go up to degree level. You earn a wage while you study, and your employer and the government pay for the training. The apprentice minimum wage is £8 an hour from April 2026. It applies if you're under 19, or 19 or over in your first year, after which you move to the normal minimum wage for your age (GOV.UK). Popular areas include digital and technology, engineering, financial services, healthcare and law.
Other routes:
- Employer-sponsored study: some employers pay for degrees or qualifications in return for staying with them for a set time.
- Professional qualifications: accountancy (ACCA, CIMA, ICAEW), project management and IT certifications can lead to well-paid careers without a degree.
- Part-time and distance learning: slower, but you can keep earning, and some employers contribute to fees.
The "degree vs no degree" choice depends heavily on the subject and the career. Look at graduate outcomes for your specific course and university, not national averages.
Frequently asked questions
How much student finance will I get in 2026/27?
In England for 2026/27, you can get a Tuition Fee Loan of up to £9,790 a year, plus a Maintenance Loan of up to £9,118 living with parents, £10,830 away from home outside London, or £14,135 in London. The Maintenance Loan amount depends on household income. Use GOV.UK's student finance calculator for an estimate.
When do you start paying back student finance?
On Plan 5, which covers English undergraduates starting from August 2023, you start repaying the April after you finish your course, once you earn over £25,000 a year. You repay 9% of income above that, usually through PAYE. If your income drops below the threshold, repayments stop automatically.
What is the interest rate on a Plan 5 student loan?
GOV.UK lists the Plan 5 interest rate as 4.1%, the same as Plans 1 and 4. Interest is added from the day you receive your first payment, so your balance grows while you study. Plan 2 charges between 4.1% and 6% depending on your income, and Postgraduate Loans charge 6%.
Does student loan debt get written off?
Yes. Plan 5 loans are written off 40 years after the April you were first due to repay. Plan 2, Plan 4 and Postgraduate Loans are written off after 30 years, and most Plan 1 loans after 25 years. Anything still owed at that point is cancelled, and you don't need to apply.
What is the Lifelong Learning Entitlement?
The Lifelong Learning Entitlement replaces current student finance for courses starting on or after 1 January 2027. It offers a total tuition loan of up to £39,160, about four years of full-time study, which you can use for full degrees or shorter modules across your life. Applications open from the end of October 2026.
Are there alternatives to university without debt?
Yes. Degree apprenticeships let you earn a wage while your employer and the government pay for training, so you can qualify without a student loan. The apprentice minimum wage is £8 an hour from April 2026. Employer-sponsored study and professional qualifications such as ACCA or CIMA are other options.
Conclusion
Student finance in England is generous on borrowing and gentle on repayment. You only pay 9% of what you earn above £25,000 on Plan 5, and anything left is written off after 40 years. The bigger questions are whether your course will pay off, and whether an apprenticeship or another route would suit you better.
If you're a parent helping to pay, or a graduate deciding whether to overpay, it's worth looking at the whole picture. Our debt management strategies, income-building approaches and the free UK Budget Planner are good places to start. For advice on your own situation, a personal finance review can help.
The information in this article is for educational purposes only and does not constitute financial advice. Always consult a qualified financial adviser before making financial decisions.