An emergency fund is cash you keep aside for genuine shocks: losing your job, a broken boiler, an urgent car repair. It stops one bad week turning into credit card debt. This guide covers how much to save, where to keep it in 2026, and how to build it quickly.
Key takeaways
- Target three to six months of essential spending. Based on ONS spending of £2,492 a month, MoneyWeek puts that at £7,476 to £14,952.
- Many people have very little cushion: the FCA's Financial Lives survey, cited by MoneyWeek, found 1 in 10 people have no cash savings and another 21% have less than £1,000.
- Top easy access accounts pay up to 5.00% AER in October 2026, but the best rates include temporary bonuses (Moneyfacts, 22 October 2026).
- Your savings are protected up to £120,000 per person, per authorised bank or building society by the FSCS.
- Interest is taxable above your Personal Savings Allowance (£1,000 for basic rate, £500 for higher rate taxpayers), and savings tax rates rise by 2 percentage points from April 2027.
What is an emergency fund and why do you need one?
An emergency fund is money set aside only for unexpected, essential costs. It's your first line of defence, so you don't have to borrow when something goes wrong.
Without one, most people fall back on credit cards, overdrafts or loans, which cost far more than the interest your savings earn. It also gives you room to make better decisions: you're less likely to sell investments at a bad time or take the first job offer out of panic.
What counts as a genuine emergency?
- Job loss or a big drop in income
- Urgent medical, dental or vet bills
- Car repairs you need to get to work
- Essential home repairs, such as a boiler breakdown or roof leak
- Emergency travel for family reasons
What doesn't count: holidays, Christmas, a new TV or routine car servicing. These are predictable, so plan for them in separate savings pots.
How much should you have in your emergency fund UK?
Most people should aim for three to six months of essential spending. MoneyWeek's guide, using ONS figures of £2,492 a month, works this out at £7,476 for three months and £14,952 for six (MoneyWeek, updated April 2026). For retirees it suggests one to three years of essential spending, because there's no salary to rebuild the pot.
| Your situation | Suggested target | Example at £2,500/month essentials |
|---|---|---|
| Stable job, two incomes, no dependants | 3 months | £7,500 |
| Single income or children | 4 to 6 months | £10,000 to £15,000 |
| Self-employed, contractor or irregular income | 6 months or more | £15,000+ |
| Retired, drawing from savings | 1 to 3 years of essentials | £30,000 to £90,000 |
To find your number, add up your essential monthly costs: rent or mortgage, council tax, energy and water, food, transport, insurance, minimum debt payments and childcare. Leave out spending you could cut quickly in a crisis, such as eating out or subscriptions.
Take Action: Use the UK Budget Planner to total your essential spending, then multiply by three for your minimum target.
Where should you keep your emergency fund UK?
An easy access savings account is the best home for most emergency funds. You can withdraw without penalty, it pays interest, and it's protected by the FSCS up to £120,000 per person, per authorised firm.
Here are the main options as of October 2026:
| Option | Typical return | Access | Watch out for |
|---|---|---|---|
| Top easy access savings | Up to 5.00% AER (incl. bonus) | Same or next day | Bonuses expire after 6-12 months |
| Limited access savings | Around 4.5% AER | A few free withdrawals a year | Extra withdrawals may cost interest |
| Easy access cash ISA | Varies, compare with non-ISA rates | Same or next day | Uses your £20,000 ISA allowance |
| Premium Bonds | 3.80% prize fund rate (not guaranteed) | A few working days | You may win less than the average |
| Current account | Often 0% | Instant | Inflation erodes it |
Easy access savings accounts
The best easy access rates on Moneyfacts on 22 October 2026 were LemFi at 5.00% AER (including a 1.89% bonus for six months), Zopa at 4.56% (including a 1.05% bonus for 12 months, on a limited access pot with three penalty-free withdrawals a year) and Tembo Money at 4.55% (including a 1.55% bonus for 12 months). Because those headline rates rely on bonuses, set a reminder to move your money when the bonus ends. Compare this month's best buys in our best savings accounts guide.
Bank Rate is 3.75%, after the Bank of England held it 6-3 on 17 September 2026, with the next decision due on 5 November 2026. Three members voted for a rise, so easy access rates could move either way.
Cash ISAs
A cash ISA keeps interest tax-free, which matters more from next year. The Personal Savings Allowance lets basic rate taxpayers earn £1,000 of interest tax-free (£500 for higher rate, nothing for additional rate). A £15,000 fund earning 4.5% makes £675 a year, which a higher rate taxpayer would pay tax on above £500. From 6 April 2027, savings income tax rates rise to 24%, 44% and 49% (HMRC Budget 2026 rates), while the cash ISA limit stays at £20,000 for everyone after the planned cut was scrapped (see our Budget 2026 guide). See our ISA allowance guide.
Premium Bonds
NS&I set the Premium Bonds prize fund rate at 3.80% from the July 2026 draw, with odds of 22,000 to 1 per £1 bond, and you can hold up to £50,000. Your money is 100% backed by HM Treasury and prizes are tax-free, but returns aren't guaranteed and many holders win less than the average rate.
Where not to keep it
- Fixed-term savings: you can't get the money out. Once your fund is full, though, extra savings you won't need for a year can earn more. See whether fixed rates above 5% are worth locking in.
- Investments: values can fall just when you need the cash.
- Your current account: too tempting to spend, and usually earns little or nothing.
Take Action: Check your fund is with an FSCS-protected provider and that it's not spread across brands sharing one banking licence if you hold more than £120,000.
How to build an emergency fund fast UK
Start with a £1,000 mini target, then automate the rest. £1,000 covers most car repairs and appliance breakdowns, and getting there quickly builds momentum.
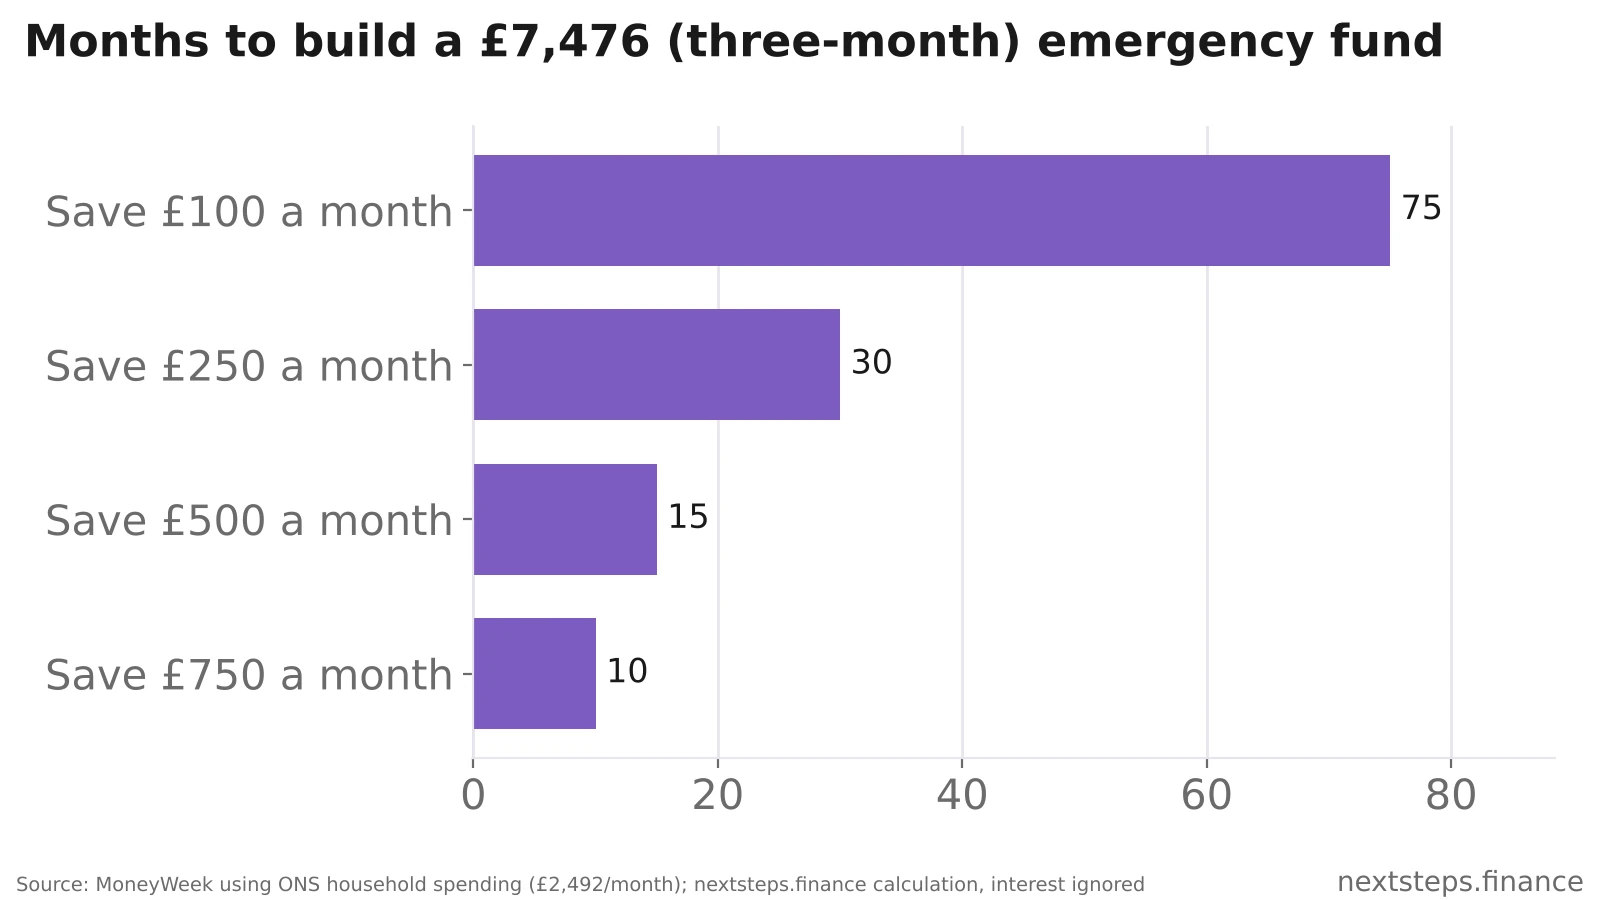
- Automate on payday. Set up a standing order the day you're paid, or use an app like Plum that puts money aside automatically using savings rules you switch on. Even £100 a month gets you to £1,000 in 10 months.
- Redirect windfalls. Tax refunds, bonuses and money from selling unused items can go straight into the pot.
- Run a one or two month spending freeze on non-essentials to give it a boost.
- Add side income. Extra shifts, freelancing or selling things you no longer need all help. Our side hustles guide has more ideas.
- Keep it separate. A different provider from your current account makes it less tempting to dip in.
Take Action: Set up an automatic transfer today, even £25 a month. You can increase it once the habit sticks.
Emergency fund vs paying off debt, pensions and a house deposit
Build a small buffer first, then tackle expensive debt, then finish the full fund. That order stops a surprise bill pushing you back onto a credit card while you're paying it off.
A practical order many UK savers use:
- Build a £1,000 starter emergency fund
- Join your workplace pension and get the full employer contribution (it's free money: see our employer pension guide)
- Pay off high-interest debt such as credit cards and overdrafts (our debt guide covers how)
- Complete your three to six month emergency fund
- Move on to other goals: a house deposit, extra pension contributions or investing
Buying a home soon? You may run a slightly smaller fund while saving a deposit, but plan to rebuild it after you move, as homeowners face repair bills renters don't.
Common emergency fund mistakes to avoid
The biggest mistake is leaving the money where it earns nothing. With September 2026 CPI inflation at 3.5%, £10,000 earning 0% loses roughly £350 of buying power in a year.
- Staying in an expired bonus rate. Many top rates drop by 1-2 percentage points after 6-12 months.
- Using it for non-emergencies. Holidays and Christmas need their own savings pots.
- Never updating the target. A new baby, a mortgage or going self-employed should all trigger a review.
- Keeping too much in cash. More than six to 12 months of spending in cash (unless you're retired) may mean missing out on long-term growth in a pension or stocks and shares ISA.
- Forgetting tax. A large fund can exceed your Personal Savings Allowance, especially after rates rise in April 2027.
When and how to use your emergency fund
Use it when the cost is urgent, essential and unexpected. If you can cover a cost from next month's pay without missing bills, consider doing that instead.
- Take only what you need. If a £500 repair comes out of a £10,000 fund, the rest stays put.
- Refill it quickly. Pause other savings goals and redirect that money until the fund is back to target.
- Learn from it. If the same type of "emergency" keeps happening, such as car repairs, budget for it as a regular cost.
Using your emergency fund isn't a failure. It's exactly what it's for.
Take Action: Write down three situations that would justify using the fund. Deciding in advance makes it easier under pressure.
Conclusion
Aim for three to six months of essential spending, keep it in an FSCS-protected easy access account, and automate your saving. In October 2026, top easy access accounts pay up to 5.00% AER including bonuses, so moving money out of a 0% current account is worth doing today. For more help, see the complete budgeting guide, the UK Budget Planner and MoneyHelper's emergency savings guide.
The information in this article is for educational purposes only and does not constitute financial advice. Rates and offers change; always check the provider's terms before opening an account.
Related guides
- Best Savings Accounts UK: Top Rates for October 2026
- No Emergency Fund? 9 Alternatives to Protect Yourself
- Complete Guide to Budgeting UK: How to Budget Money in 2026
Frequently Asked Questions
How much should I have in an emergency fund UK?
Most people should aim for three to six months of essential spending. Using ONS spending of £2,492 a month, that's about £7,476 to £14,952. Lean towards three months if you have a stable job and two incomes, and six months or more if you're self-employed, a single earner or have children.
Is £10,000 a good emergency fund?
£10,000 is a good emergency fund for many UK households, covering about four months of essential spending at £2,500 a month. Whether it's enough depends on your costs and job security. If you're self-employed or support a family on one income, you may want closer to six months.
Where is the best place to keep an emergency fund UK?
An FSCS-protected easy access savings account is the best place for most people, because you can withdraw at any time and still earn interest. In October 2026 the top easy access rates are around 4.5% to 5% AER including bonuses. Easy access cash ISAs and Premium Bonds are alternatives.
Should I keep my emergency fund in a cash ISA?
A cash ISA can be a good home if you'd otherwise pay tax on your interest. Basic rate taxpayers can earn £1,000 of interest tax-free and higher rate taxpayers £500. Savings tax rates rise by two percentage points from April 2027, making ISAs more valuable, but make sure the ISA allows instant withdrawals.
Is 3 months emergency fund enough?
Three months is enough for many people with secure jobs, two household incomes and no dependants. If your income is irregular, you work in an unstable industry or others rely on you, six months gives more protection, as it can take several months to find a new job.
Should I save an emergency fund or pay off debt first?
Build a small £1,000 emergency fund first, so a surprise bill doesn't send you back to a credit card. Then focus on clearing high-interest debt, before finishing your full three to six month fund. Keep paying at least the minimum on all debts throughout.