Switching your current account is one of the easiest ways to earn £150-£300 in a few weeks. The switch itself is free, takes seven working days and is guaranteed. The catch is the small print: each bank wants a minimum pay-in, a set number of Direct Debits and, increasingly, some card spending. This guide lists every offer we could verify on 21 October 2026, what you need to do for each, and who's excluded.
Key takeaways
- Barclays pays the most on paper (up to £300), but £150 of it comes as £30 a month for five months, so it needs ongoing card use.
- HSBC (£220) and First Direct (£210) pay the most upfront. You can't get both, because First Direct excludes anyone who's opened an HSBC current account since 2018.
- Lloyds' £200 needs no pay-in at all, just three Direct Debits, but you must start the switch by 9 December 2026.
- First Direct's extra £35 only applies to accounts opened by 2 December 2026.
- Switching bonuses don't count as interest, so they won't use up your Personal Savings Allowance.
What are the best bank switching offers right now?
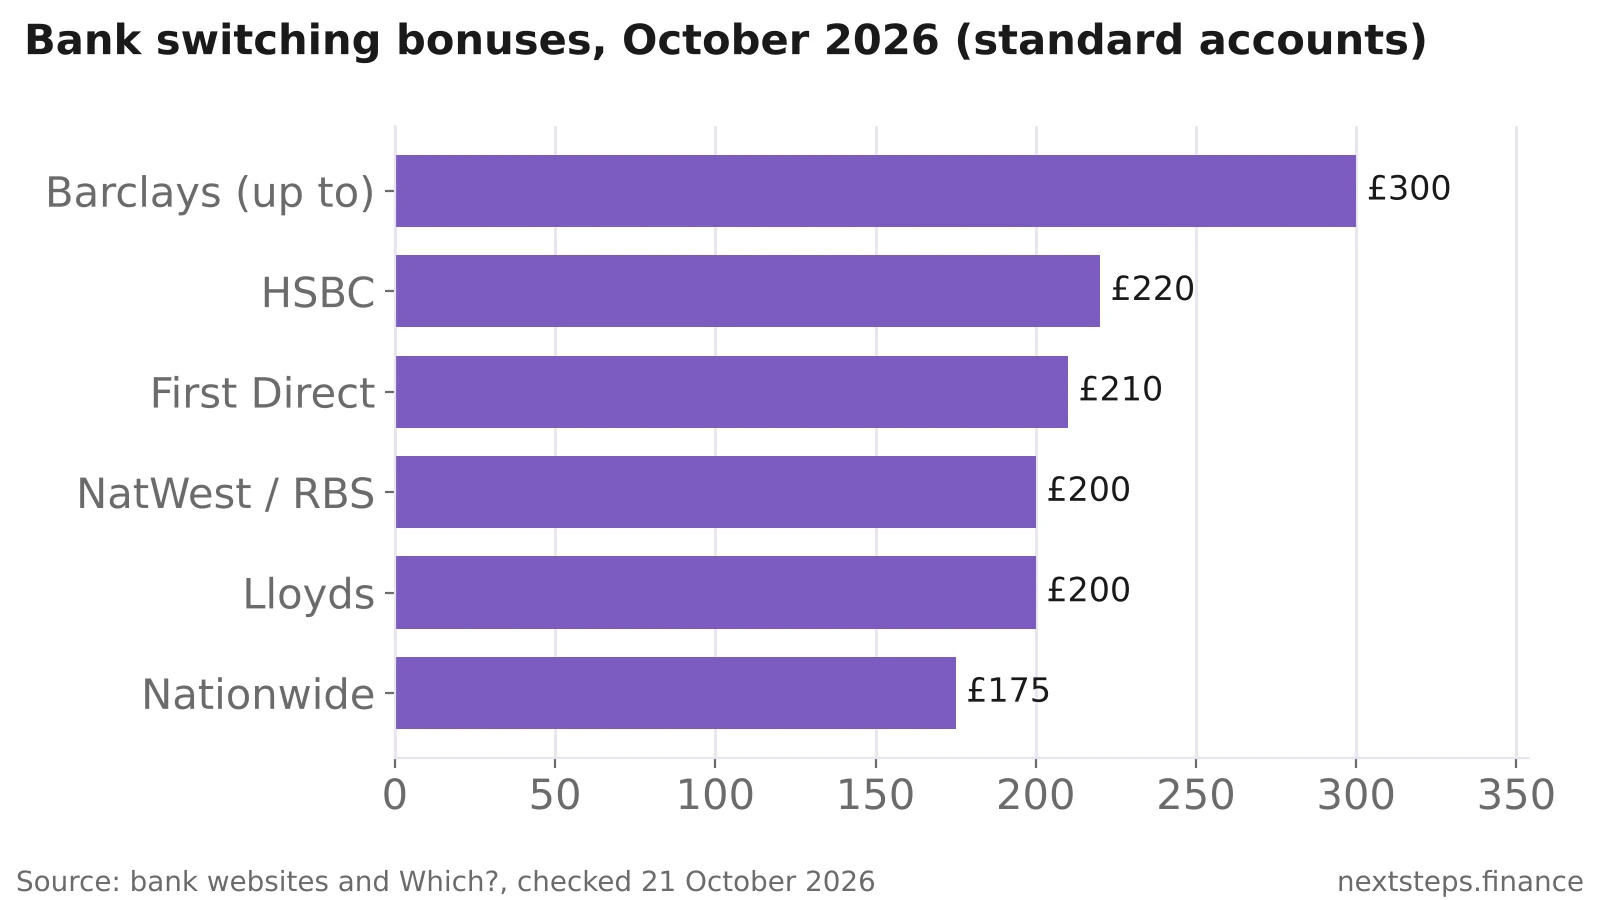
Six banks are paying cash for a full switch this month. Here's how they compare, with the main requirement for each:
| Bank | Bonus | What you need to do | Monthly fee | Main exclusion |
|---|---|---|---|---|
| Barclays | Up to £300 (£150 + £30 a month for 5 months) | Pay in £2,000 within 30 days, move 3 Direct Debits. For the monthly £30: pay in £2,000 and make 10 card payments each month | £0 (Blue Rewards optional) | Had a Barclays current account on 1 Oct 2026 |
| HSBC | £220 | Within 60 days: pay in £2,000, spend £500 on the debit card, move 2 Direct Debits. Apply in the HSBC app | £0 | Existing HSBC or First Direct customers |
| First Direct | £210 (£175 + £35 boost) | Within 45 days: pay in £1,000, make 5 card payments, move 2 Direct Debits or standing orders, log on to digital banking | £0 | Ever held a First Direct product, or opened an HSBC current account since 1 Jan 2018 |
| NatWest / RBS | £200 | Within 60 days: pay in £1,250 and log in to the app (Select or Reward account) | £0 (Select), £2 (Reward) | Had a NatWest Group switching bonus before; joint accounts excluded |
| Lloyds | £200 | Move at least 3 active Direct Debits (Club Lloyds and above). Start by 9 Dec 2026 | £5, refunded if you pay in £2,000 a month | Switching from Halifax or Bank of Scotland; had a Lloyds Banking Group bonus since 1 Jan 2023 |
| Nationwide | £175 | Pay in £1,000 and make 1 card payment within 31 days, move 2 Direct Debits | £0 (FlexAccount, FlexDirect), £18 (FlexPlus) | Switching from Nationwide or Virgin Money |
Premier accounts pay more if you qualify. HSBC Premier and NatWest Premier both offer £500, but you need roughly £100,000 of income or savings. Barclays Premier offers up to £600 if you pay in at least £5,000 of salary within 30 days.
Short-lived extras: Santander is offering new Edge customers a £100 Amazon voucher until 26 October 2026.
Offers change often and can be withdrawn without notice. Check the bank's own terms on the day you apply.
Take Action: Pick the offer whose pay-in and Direct Debit rules you can meet with your normal salary and bills. The highest headline figure isn't always the easiest to earn.
How does the Current Account Switch Service work?
The Current Account Switch Service (CASS) moves your balance, Direct Debits, standing orders and incoming payments to your new bank in seven working days. It's free, and almost every UK bank and building society uses it. Nearly all switching bonuses require a full CASS switch, so opening a new account and moving money yourself won't qualify.
What happens:
- You open the new account and choose a switch date.
- Your new bank arranges everything with your old bank.
- On the switch date, your balance, Direct Debits and standing orders move across, and your old account closes.
- For 36 months, any payments sent to your old account are automatically redirected.
The Current Account Switch Guarantee means that if anything goes wrong because of the switch, your new bank refunds any interest or charges. Read our step-by-step guide to how to switch bank accounts with CASS for the details.
Which switching offer should you choose?
It depends mainly on how much you pay in each month and whether you've banked with that group before:
- You earn £2,000+ a month and will use the card: Barclays (up to £300) or HSBC (£220).
- You want the least effort: Lloyds (£200, no pay-in requirement, just three Direct Debits) or NatWest/RBS (£200 for £1,250 paid in).
- You've never banked with HSBC or First Direct: First Direct's £210 is one of the best-rated accounts for customer service.
- You bank with a building society or want a mutual: Nationwide (£175).
Remember the bank groups: HSBC and First Direct are one group, as are Lloyds, Halifax and Bank of Scotland, and NatWest, RBS and Ulster Bank. A past bonus or account with one usually rules you out of the others.
Digital banks vs high street banks: which pays more?
High street banks pay the cash. All of this month's £175-£300 offers come from traditional banks. App-only banks rarely pay a CASS switching bonus.
Digital banks compete on features instead. Monzo, Starling and Chase offer fee-free spending abroad, instant notifications, savings pots and budgeting tools. Monzo and Revolut also run refer-a-friend rewards from time to time. Many people do both: take a high street switching bonus for their main account, and use a digital bank alongside it for budgeting and travel. See our Monzo vs Starling vs Revolut comparison for help choosing.
What criteria must you meet to qualify?
Every offer has its own rules, but most check the same things:
- A full CASS switch, closing your old account. Partial switches usually don't count.
- A minimum pay-in, usually £1,000-£2,000 within 30-60 days.
- Direct Debits: usually two or three must move across with the switch. New ones set up afterwards often don't count.
- Card spending: HSBC, First Direct and Barclays now require debit card payments.
- New customer status: no current account or switching bonus with that bank (or group) since a cut-off date.
- Age and residency: 18 or over and a UK resident.
Most banks run a soft or hard credit check when you open an account. If you're applying for a mortgage soon, space out new accounts.
Are There Any Catches or Hidden Costs to Consider?
While bank switching offers appear straightforward, several potential pitfalls could reduce their value or create unexpected costs.
Monthly account fees represent the biggest ongoing consideration. Some accounts with generous switching bonuses charge £10-£25 monthly fees after an introductory period. Always calculate whether the annual fee exceeds the switching bonus value.
Overdraft charges can be particularly costly if you occasionally go into the red. Most arranged overdrafts cost around 40% EAR, while premium accounts often include fee-free overdraft buffers.
Minimum balance requirements might apply to maintain certain benefits or avoid fees. Some accounts require you to keep £1,000-£5,000 in the account to qualify for the best interest rates or avoid charges.
Direct debit requirements often extend beyond the initial qualifying period. Some banks require you to maintain a certain number of active direct debits to keep earning rewards or avoid fees.
Credit impact is minimal for most switches, but opening multiple accounts in quick succession could affect your credit score. Space out applications if you're planning a mortgage application soon.
The Financial Conduct Authority requires banks to be transparent about charges, but it's worth reading the full terms and conditions before switching.
Take Action: Calculate the total value over 12-24 months, including any ongoing fees, before choosing an account based solely on the switching bonus amount.
How can you earn more from switching?
- Switch more than once. Once one bonus has paid out, you can switch the same account again to another bank with an offer, as long as that bank's rules allow it.
- Keep a log of when you held each bank's account and received each bonus, so you know when you're eligible again.
- Use a joint account carefully. Some offers exclude joint accounts (NatWest), and others pay only once per joint account (Nationwide).
- Time it. Banks often launch bigger offers in spring and autumn, and add short boosts like First Direct's £35.
- Pair it with a good savings account. Current accounts rarely pay good interest, so keep your emergency fund in one of the best savings accounts.
What About Business and Joint Account Switching Offers?
Business and joint account switching presents additional opportunities, though with different criteria and often larger potential bonuses.
Business account switching offers can be particularly generous, with bonuses ranging from £200-£500 for qualifying business customers. However, requirements are typically more stringent:
- Minimum monthly turnover requirements (often £1,000-£5,000)
- Business banking relationship rather than just personal banking
- Longer qualifying periods to demonstrate genuine business use
Joint account switching follows similar principles to personal accounts, but both account holders typically need to be new customers to qualify for bonuses. Some banks offer the full bonus to joint accounts, while others split the reward.
Student account switching often includes different incentives like interest-free overdrafts, railcards, or shopping discounts rather than cash bonuses.
For comprehensive guidance on different account types, explore our banking topic page which covers personal, business, and specialist account options.
Related guides
- How to Switch Bank Accounts UK: Complete CASS Guide
- Best Bank Accounts UK
- Monzo Referral Bonus Guide
FAQ
What is the best bank switching offer in the UK right now?
As of 21 October 2026, Barclays has the largest headline offer at up to £300, but only £150 is paid upfront. HSBC's £220 is the biggest single payment for a standard account, followed by First Direct's £210, which includes a £35 boost for accounts opened by 2 December 2026.
Are bank switching bonuses taxable?
Generally no. A switching bonus isn't interest, so it doesn't count towards your Personal Savings Allowance, and HMRC doesn't normally treat a one-off incentive like this as taxable income. Interest you earn on the account balance is different and is taxable above your allowance.
How long does a bank switch take?
A full switch through the Current Account Switch Service takes seven working days from the date you choose. Your Direct Debits, standing orders and balance move automatically, and payments to your old account are redirected for 36 months.
Can I get a switching bonus more than once?
Usually once per bank or banking group, within a set period. Most banks exclude anyone who's received their switching bonus or held their current account since a cut-off date, which is often several years back. You can still switch to a different bank group and claim its offer.
Do I have to close my old account to get a switching bonus?
Yes, for almost all offers. The bonus requires a full switch using the Current Account Switch Service, which closes your old account as part of the process. A partial switch, or opening an account and moving money manually, normally won't qualify.
Does switching bank affect my credit score?
Opening a new account usually involves a credit check, which can cause a small, temporary dip. One or two switches a year shouldn't cause problems, but avoid opening several accounts just before a mortgage or loan application.
The information in this article is for educational purposes only and does not constitute financial advice. Offers were checked on 21 October 2026 and can change or be withdrawn at any time; always check the bank's terms before applying.
Sources: Which? best switching deals, first direct, Barclays switch offer, Current Account Switch Service.