Credit union savings accounts in the UK work differently from ordinary bank savings. A credit union is owned by its members, who pool savings to provide services and lend to one another. Most pay a dividend from any surplus rather than a guaranteed interest rate.
HM Treasury announced a proposed membership change on 11 November 2026. It could help more relatives join, but is not yet in force. This guide explains the current rules, savings returns, protection and what to check before joining.
For the wider choice of current and savings accounts, see our UK banking guide.
Key takeaways
- Credit unions are not-for-profit, member-owned organisations. Members save with the union and the money can be lent to other members.
- You normally need a common bond, such as living or working in an area, sharing an employer or occupation, or belonging to an association.
- Most credit unions pay an annual dividend that can be low or zero; some offer a fixed interest rate instead.
- Eligible deposits with a UK-authorised credit union are covered by the FSCS up to £120,000 per eligible person, per authorised firm.
- The Government announced a proposed Great Britain membership change on 11 November 2026. It is not yet law.
- The legal maximum loan interest rate is 3% a month in Great Britain and 1% a month in Northern Ireland.
What is a credit union and how does it work?
A credit union is a financial co-operative owned and run by its members. Members save with the organisation, and those funds help it provide loans and other services to the same membership rather than generate returns for external shareholders.
Section 1A of the Credit Unions Act 1979 sets out the common-bond framework for Great Britain. A credit union's rules restrict membership to people who meet one or more qualifying connections. Members have a say in how it is run: MoneyHelper notes that every member gets a vote at the annual general meeting, however much they save.
A credit union is not necessarily a full current account. Check whether the union offers the card, transfers and bill-payment features you need.
Who can join a credit union in the UK?
You can join if you meet the credit union's common bond and any additional conditions in its rules. Common bonds in Great Britain can include:
- Locality: living or working in a defined geographical area.
- Employer: working for a named employer or group of employers.
- Occupation: working in a particular profession or industry.
- Association: belonging to a qualifying organisation or sharing another approved connection with its members.
Some unions have multiple common bonds, so you may qualify through work even if you live elsewhere. Under current Great Britain rules, a relative in the same household as a qualifying member may also qualify if the union's rules allow it. Check whether a fee, opening deposit or regular saving is required.
MoneyHelper's credit union savings page links to the Find Your Credit Union (FYCU) search for Great Britain, and to the Irish League of Credit Unions and the Ulster Federation of Credit Unions for Northern Ireland.
Do not assume that a relative can join simply because someone in your family already belongs. The union's current rules still matter, particularly while the proposed changes below are being considered.
What are the proposed November 2026 credit union reforms?
The Government has proposed making it easier for relatives and household members to join a credit union when an existing member moves away. HM Treasury announced the proposal on 11 November 2026, but it is not yet in force.
Under the proposal, a member who has moved out of the credit union's area could still refer a relative or household member. Today, the member must live in the area to do this. HM Treasury says more than 50,000 people across Great Britain who can't currently refer a relative would be able to, based on Bank of England data. That is an estimate of who could refer, not a forecast of new members.
The same announcement lists other reforms aimed at doubling the size of the sector: raising the membership cap on local credit unions from 3 million to 10 million, letting students join their local credit union, and letting members of employment-based credit unions keep referring relatives after they retire.
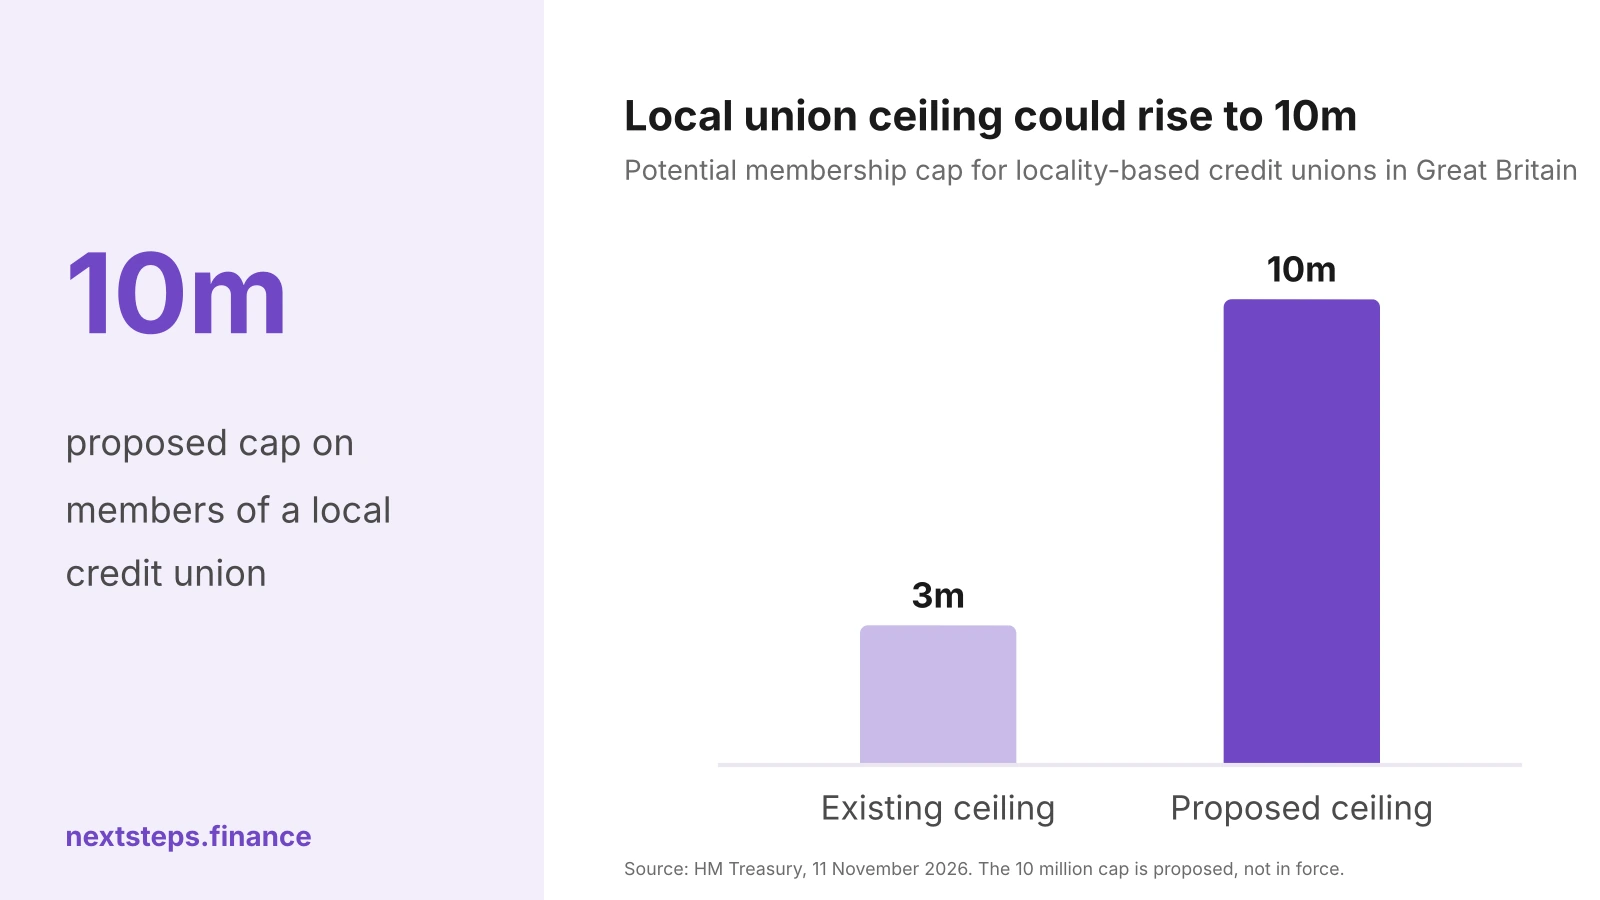
The 10 million figure is a cap on how many members a local credit union could have, not a claim that any union is that big. The Government announced the changes at the second reading of the Financial Services and Markets Bill in Parliament, so they remain proposals and are not yet law. Until they are passed and take effect, use the existing membership rules.
These proposals apply to Great Britain. Northern Ireland has separate credit union legislation, so do not assume the same changes or timetable apply there.
How do credit union savings accounts pay interest or dividends?
Most credit union savings accounts pay an annual dividend if the organisation has a surplus; some pay a fixed rate of interest instead. A dividend is not guaranteed and can be reduced or zero if the credit union has not made enough surplus to distribute.
MoneyHelper says members vote on the dividend at the annual general meeting, and it varies with how much profit the credit union made that year. Dividends can be low, or even zero, if there's no surplus. A past rate is not a guarantee.
Before opening an account, ask whether the return is guaranteed interest or a discretionary dividend, when it is calculated and paid, and whether withdrawals are restricted. Credit union savings accounts generally don't charge fees, but check the provider's terms. You can usually withdraw at any time, though notice accounts make you wait, and not every union offers a debit card or online transfers.
Are credit union dividends taxable?
They can be. The word "dividend" can be confusing: HMRC says share or loan interest paid by a credit union, including member dividends, is normally paid without tax deducted and is taxed on the member as interest. It is not treated like a dividend from an ordinary company, and MoneyHelper notes it's up to you to declare it.
Your Personal Savings Allowance or starting rate for savings may cover some or all of the amount, depending on your wider income. Do not assume the company dividend allowance applies. See HMRC's credit union taxation guidance if you need to check the treatment.
Are credit union savings protected by the FSCS?
Eligible deposits held with a UK-authorised credit union are covered by the Financial Services Compensation Scheme (FSCS) up to £120,000 per eligible person, per authorised firm. The limit applies across eligible accounts with the same firm, not separately to each account.
The Bank of England raised the limit from £85,000 to £120,000 from 1 December 2025, and its announcement names credit unions alongside banks and building societies. FSCS protection is compensation if an authorised firm fails; it does not guarantee a particular dividend, interest rate or level of service.
Check that the credit union and the product are eligible before depositing money. Use the FSCS's own firm checker rather than relying only on a logo or trading name.
Our FSCS protection guide explains how the limit works across accounts and banking licences.
Can you borrow from a credit union, and what does it cost?
Credit unions also lend to members, often for smaller amounts. You may need to have been a member for a period or to have built up some savings first. Each union sets its own lending policy and must assess whether repayments are affordable.
There are legal limits on the interest a credit union can charge:
| Nation | Maximum monthly interest | Legal basis |
|---|---|---|
| England, Scotland and Wales | 3% | Credit Unions (Maximum Interest Rate on Loans) Order 2013 |
| Northern Ireland | 1% | Credit Unions (Northern Ireland) Order 1985 |
The Credit Unions (Maximum Interest Rate on Loans) Order 2013 raised the Great Britain limit from 2% to 3% a month. Northern Ireland's separate legislation sets a limit of 1% a month on the amount of the loan outstanding, inclusive of all administrative and other expenses, in Article 28 of the 1985 Order.
These are legal ceilings, not typical prices. Compare the actual APR, total amount repayable and term with other borrowing options. A credit union loan is still debt: missing payments can cause financial difficulty.
If you are already struggling to meet repayments, do not take out another loan without getting help. Our guide to getting out of debt explains free UK debt-advice options.
How do you compare and join a credit union?
Check the common bond first, then compare the account terms rather than choosing on the headline dividend alone.
- Find eligible unions. Search by postcode, employer, occupation or association using the directory for your nation.
- Check the membership rules. Ask whether you need an opening deposit, joining fee, regular saving or a waiting period.
- Understand the return. Find out whether the account pays interest or a discretionary dividend, when it is paid and whether it can be zero.
- Check access. Confirm withdrawal times, notice periods, transfer options, branch access and whether a debit card is available.
- Check protection. Confirm that the credit union is authorised and that the deposit is eligible for FSCS protection.
- If borrowing, compare the full cost. Ask for the APR, total repayable, repayment schedule and any membership or savings conditions.
A credit union may suit someone who values a member-owned, community-based service and meets its membership rules. It may not suit someone who needs a particular branch network, guaranteed interest or unrestricted instant access.
A conventional easy-access account, notice account or cash ISA may be a better fit if your priority is a stated interest rate or a wider choice of providers. Our savings guide explains the main account types, and the best savings accounts comparison is a starting point for checking alternatives.
This is general information, not personal financial advice. Read the credit union's own terms before making a decision.
FAQ
Can anyone join a credit union?
No. You normally need to meet a common bond, such as living or working in a particular area, working for a named employer, following a qualifying occupation or belonging to an association. Each credit union sets its own detailed membership rules, so check its criteria before applying.
Can I join a credit union if I live outside its area?
Possibly. You may qualify through your employer, occupation or an association instead of where you live. Some unions have several common bonds. The proposed 2026 changes could widen family referrals in Great Britain, but they are not yet in force, so check the current rules.
Are credit union savings covered by the FSCS?
Eligible deposits with a UK-authorised credit union are covered up to £120,000 per eligible person, per authorised firm. The limit is shared across eligible accounts with the same firm. Check the credit union's legal entity and the product's eligibility with the FSCS before depositing money.
Are credit union dividends taxable?
They can be. HMRC treats share or loan interest paid by a credit union, including member dividends, as interest for the member's tax purposes. It is normally paid without tax deducted. Your savings allowances may reduce the tax due, but the company dividend allowance does not automatically apply.
Are credit union loans cheaper than bank loans?
Not always. Each credit union sets its own rates within the legal cap of 3% a month in Great Britain (1% in Northern Ireland), and the cap is a maximum, not the rate every union charges. Compare the actual APR and total amount repayable with other options before borrowing.