Wealthify is one of the simplest ways to invest in the UK: you answer a few questions, pick one of five risk levels and it runs a ready-made portfolio for you. I've checked Wealthify's own fee, performance and offer pages today, 29 October 2026, the day after a Budget that kept the £20,000 ISA allowance in place.
The short version: it's easy, well backed and fairly priced for a managed service, but it isn't cheap compared with doing it yourself, and its cautious plans have barely grown over the last five years. Here's what you'd actually pay, what you'd have earned, and who it suits.
Key takeaways
- Wealthify's management fee is 0.6% a year, falling to 0.3% only on the part of a Wealthify Personal Pension above £100,000 (Wealthify fees).
- Fund and trading costs are about 0.14% a year on Original plans and 0.46% on Ethical plans, making a total of roughly 0.74% or 1.06%.
- The minimum to open a Stocks and Shares ISA or Junior ISA is now £1,000, and £5,000 for a pension or General Investment Account. You can top up from £1.
- New customers referred by a friend get £50 after investing £1,000 in an ISA or JISA and leaving it for six months (Wealthify refer a friend).
- Separate ISA cashback of £50 to £1,500 is available if you register by 17 December 2026 and deposit or transfer £5,000 or more (Wealthify ISA cashback).
What is Wealthify and is it safe?
Wealthify is a UK digital investment manager (a "robo-adviser") owned by Aviva, and it is authorised and regulated by the Financial Conduct Authority under FCA number 662530. Your money is invested in funds held for you, not lent to Wealthify.
You choose a risk level, from Cautious, Tentative, Confident, Ambitious to Adventurous, and a style: Original or Ethical. Wealthify then picks the funds, rebalances them and adjusts the mix over time. You don't choose individual shares or funds.
Wealthify says it manages investments for more than 100,000 people. Eligible investments in its ISA, Junior ISA and General Investment Account are covered by the FSCS up to £85,000 if the firm fails, though that protection doesn't cover your investments falling in value. Pension protection depends on the custodian.
| Product | Minimum to open | Notes |
|---|---|---|
| Stocks and Shares ISA | £1,000 | Top-ups from £1 |
| Junior ISA | £1,000 | Top-ups from £1 |
| Personal Pension (SIPP) | £5,000 | Payments from £50; fee 0.3% above £100,000 |
| General Investment Account | £5,000 | Top-ups from £1 |
| Easy Access Cash ISA | £1,000 | 3.35% AER variable, run with ClearBank |
There's no Lifetime ISA. Minimums are taken from Wealthify's offer and referral pages; some older pages on its site still quote lower figures, so check the sign-up screen.
Take Action: If safety is your main worry, the bigger risk isn't Wealthify going bust, it's choosing a risk level that doesn't match how long you're investing for.
How much does Wealthify cost?
Wealthify costs roughly 0.74% a year on an Original plan and 1.06% on an Ethical plan, once fund costs are added to the 0.6% fee. On £10,000 that's about £74 or £106 a year.
Wealthify's fees page says it won't charge for deposits, withdrawals, transfers or closing your plan. The fee is taken monthly based on your plan's value, so it rises as your pot grows. One thing to know: Wealthify keeps the interest on any uninvested cash in your plan rather than passing it on.
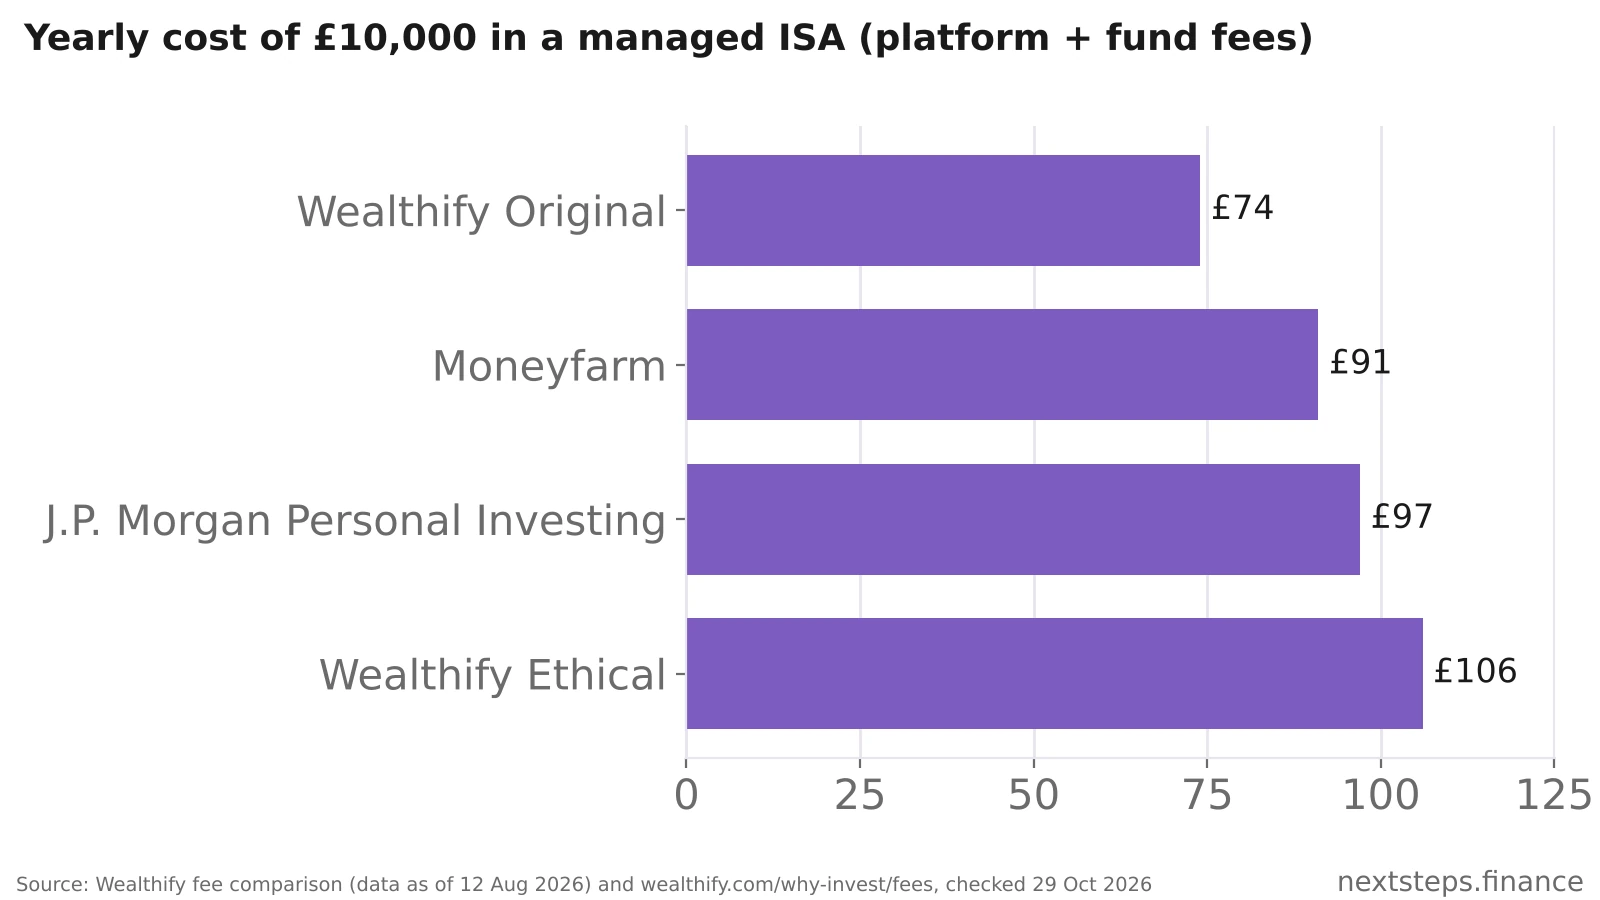
Wealthify's own comparison table, dated 12 August 2026, puts Moneyfarm at about 0.91% and J.P. Morgan Personal Investing at 0.97% for similar balances. So the Original plan is competitive among managed services. The Ethical plan is the most expensive of the four.
| Cost on a £10,000 ISA | Wealthify Original | Wealthify Ethical | InvestEngine Managed |
|---|---|---|---|
| Platform or management fee | 0.60% (£60) | 0.60% (£60) | 0.25% (£25) |
| Fund and trading costs | about 0.14% (£14) | about 0.46% (£46) | ETF costs on top |
| Approximate yearly total | £74 | £106 | £25 plus ETF costs |
| Minimum to open | £1,000 | £1,000 | £100 |
InvestEngine figures are from justETF's review dated 3 August 2026, which also notes InvestEngine charges no platform fee at all if you pick your own ETFs.
Take Action: Over 20 years, a 0.5% a year difference in costs can add up to thousands of pounds on a growing pot. Compare total cost, not just the headline fee.
What returns has Wealthify made?
Wealthify's higher-risk plans have done well since 2021, but its lowest-risk plan has gone almost nowhere. These are Wealthify's published figures after its 0.6% fee.
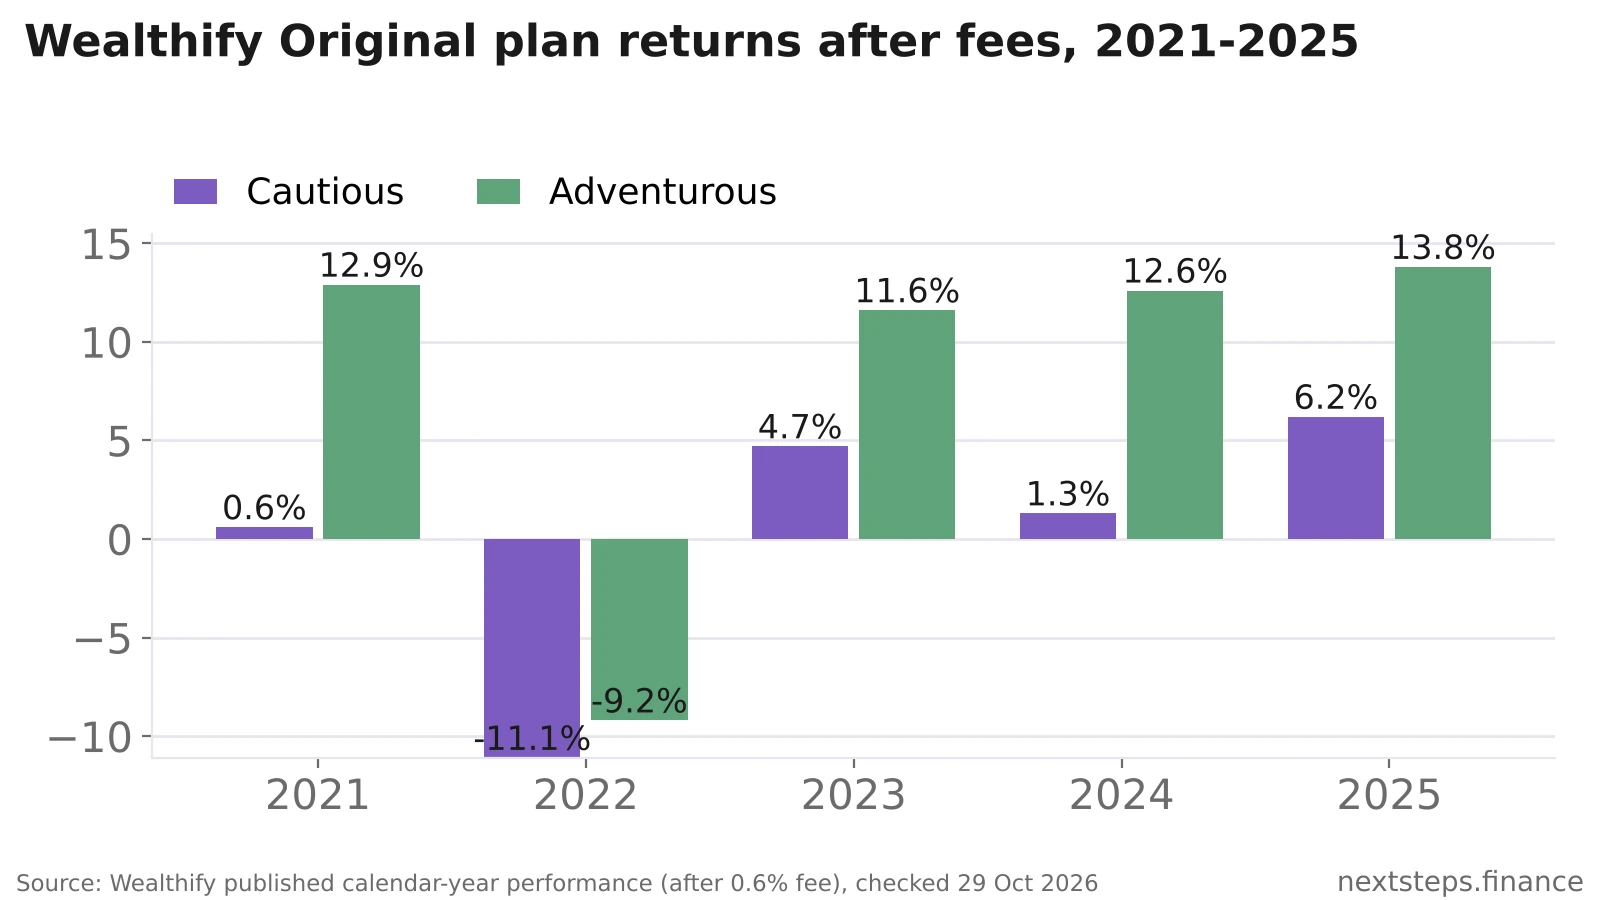
Compounding those calendar years, £1,000 in the Adventurous Original plan at the start of 2021 would have been worth about £1,466 by the end of 2025, a gain of around 47%. The same £1,000 in the Cautious plan would have been worth about £1,007, after a fall of more than 11% in 2022. Over the 12 months to 30 September 2026, Adventurous returned 17.42% and Cautious 3.79%.
The Ethical range has generally lagged: Ethical Adventurous returned 6.39% in 2025 against 13.81% for Original Adventurous. Past performance isn't a guide to the future, and these are Wealthify's own figures.
Take Action: If you'd pick Cautious, compare it with a cash ISA first. Wealthify's own Easy Access Cash ISA pays 3.35% AER variable with no risk to your capital.
What are the Wealthify welcome offers in October 2026?
There are two Wealthify offers right now, and you can't use both together. The referral pays £50, while ISA cashback pays £50 to £1,500 depending on how much you put in.
| Offer | What you get | Key conditions | Best for |
|---|---|---|---|
| Refer a friend | £50 for you (and £50 for the friend who referred you) | Invest £1,000 in an ISA or JISA (or £5,000 in a SIPP or GIA) and leave it for 6 months | Deposits under £10,000 |
| ISA cashback | £50 (£5,000+), £100 (£10,001+), £200 (£20,001+), up to £1,500 (£200,001+) | Register by 17 December 2026, deposit or transfer within 3 months, stay invested 24 months; not for existing ISA holders | Larger ISA deposits or transfers |
The referral terms (T&Cs) apply to accounts opened from 26 August 2025, have no fixed end date and say the offer can't be combined with other introductory or cashback offers. If you plan to put in more than £10,000 by mid-March, the cashback scheme pays more. Below that, the referral is the easier £50 because it needs less money and a shorter lock-in.
If the referral suits you, you can sign up to Wealthify through our link. Capital at risk - the value of investments can go down as well as up.
How do you open a Wealthify ISA?
Opening a Wealthify ISA takes about ten minutes online or in the app.
- Decide which offer you want: the referral (use a referral link) or ISA cashback (register on Wealthify's offer page first).
- Create an account and answer the questions about your goals, timeframe and attitude to risk.
- Pick a risk level and Original or Ethical. You can change these later at no cost.
- Deposit at least £1,000, or start an ISA transfer from another provider so you keep its tax-free status.
- Set up a monthly top-up if you want to keep investing.
Remember the ISA allowance is £20,000 for 2026/27 across all your ISAs, and the Budget 2026 document confirmed the planned cut to the cash ISA limit is cancelled. Our guide to the cash ISA limit after the Budget covers what changed.
Take Action: Never withdraw money from an old ISA to move it. Ask Wealthify to transfer it, or you'll lose the tax wrapper.
Wealthify vs InvestEngine and other alternatives
Wealthify suits people who want everything done for them with a big-name owner. If you're happy to choose a few ETFs, or want a cheaper managed portfolio, there are lower-cost options.
- InvestEngine charges a 0.25% platform fee on managed portfolios and nothing for DIY portfolios in an ISA, GIA or SIPP, with a £100 minimum, according to justETF. Its ready-made portfolios are built from ETFs. You can open an InvestEngine account through our link, and check its current referral bonus on sign-up. Capital at risk - the value of investments can go down as well as up.
- Moneyfarm and J.P. Morgan Personal Investing are the closest like-for-like managed rivals, at about 0.91% and 0.97% in total on Wealthify's comparison.
- A global tracker fund in any cheap ISA is the lowest-cost route if you'll leave it alone. Our best stocks and shares ISA guide compares platforms.
For a wider comparison of managed services, see our best robo-advisers UK guide.
Who is Wealthify best for?
Wealthify may suit you if you want to invest regularly without picking funds, value Aviva's backing and a simple app, and have at least £1,000 to start. It's less suited to confident DIY investors, people who need a Lifetime ISA, or anyone who'd choose the Cautious plan over cash.
Pros
- Very simple: five risk levels, two styles, no decisions after that
- No charges for deposits, withdrawals, transfers or closing
- Owned by Aviva and FCA-regulated
- ISA, Junior ISA, pension and cash ISA in one app
Cons
- 0.74% to 1.06% total yearly cost is well above DIY options
- £1,000 minimum for an ISA, higher than many rivals
- Ethical plans cost more and have recently returned less
- No interest paid on uninvested cash, and no Lifetime ISA
If you're unsure how much risk to take or whether investing beats paying off debt or overpaying a mortgage, our personal finance review can help you work through it, or speak to a regulated financial adviser.
Frequently asked questions
Is Wealthify safe?
Wealthify is owned by Aviva and authorised by the Financial Conduct Authority (FCA number 662530). Eligible ISA, Junior ISA and General Investment Account holdings are protected by the FSCS up to £85,000 if the firm fails. That protection doesn't cover investment losses, so the value of your plan can still fall.
Can you lose money with Wealthify?
Yes. Wealthify invests in funds whose value goes up and down. In 2022 its Original Cautious plan fell 11.05% and its Adventurous plan fell 9.18% after fees, according to Wealthify's own figures. Investing usually suits money you can leave for at least five years.
How much does Wealthify charge?
Wealthify charges a 0.6% annual management fee, plus fund and trading costs of about 0.14% for Original plans or 0.46% for Ethical plans. That's about £74 a year on £10,000 for Original, or £106 for Ethical. There are no deposit, withdrawal, transfer or exit fees.
What is the minimum investment for Wealthify?
You need £1,000 to open a Wealthify Stocks and Shares ISA or Junior ISA, and £5,000 for a Personal Pension or General Investment Account, according to Wealthify's October 2026 offer pages. After opening, you can top up ISAs and the GIA from £1, and pension payments start at £50.
Is Wealthify better than Moneyfarm?
On cost, Wealthify's Original plan is cheaper: about 0.74% a year in total against roughly 0.91% for Moneyfarm, according to Wealthify's comparison dated 12 August 2026. Wealthify's Ethical plan, at about 1.06%, costs more than both. Check each provider's current fee page and minimums before deciding.
Does Wealthify have a sign-up bonus?
Yes. New customers referred by a friend get £50 after investing £1,000 in an ISA or JISA for six months. Alternatively, Wealthify's ISA cashback pays £50 to £1,500 for deposits or transfers of £5,000 or more if you register by 17 December 2026. You can't combine the two.
The bottom line
Wealthify is a solid, simple managed ISA from a trusted owner, and at about 0.74% a year its Original plan is fairly priced for a fully managed service. The trade-off is cost: hands-on investors can pay a fraction of that at InvestEngine or with a tracker fund, and the Cautious plan hasn't beaten cash over five years. If you go ahead, pick the referral for smaller deposits or the ISA cashback for £10,000 or more, and choose a risk level that matches how long you'll invest.
Capital at risk - the value of investments can go down as well as up.