American Express has two cashback cards, and the right one comes down to a single number: how much you'll put on the card each year. Here's the comparison, with the maths at different spending levels.
Foundations
Amex Cashback Everyday vs Platinum Cashback: Which Pays More?
Amex Cashback Everyday vs Platinum Cashback compared for 2026. £0 vs £25 fee, 2% vs 5% intro offers, 0.5%–1% vs 0.75%–1.25% and the £10,000 break-even point.
Key takeaways
- Everyday: no fee, Representative 29.1% APR variable. Platinum Cashback: £25 a year, Representative 34.6% APR variable (ClearScore, 22 Sep 2026). Credit is subject to status.
- Intro offers: Everyday pays 2% for 12 months, up to £200 (American Express); Platinum Cashback pays 5% for three months, up to £125 (American Express).
- Ongoing: Everyday 0.5% up to £10,000, 1% above. Platinum Cashback 0.75% up to £10,000, 1.25% above.
- Minimum spend: Everyday pays nothing in a year with under £3,000 of spending.
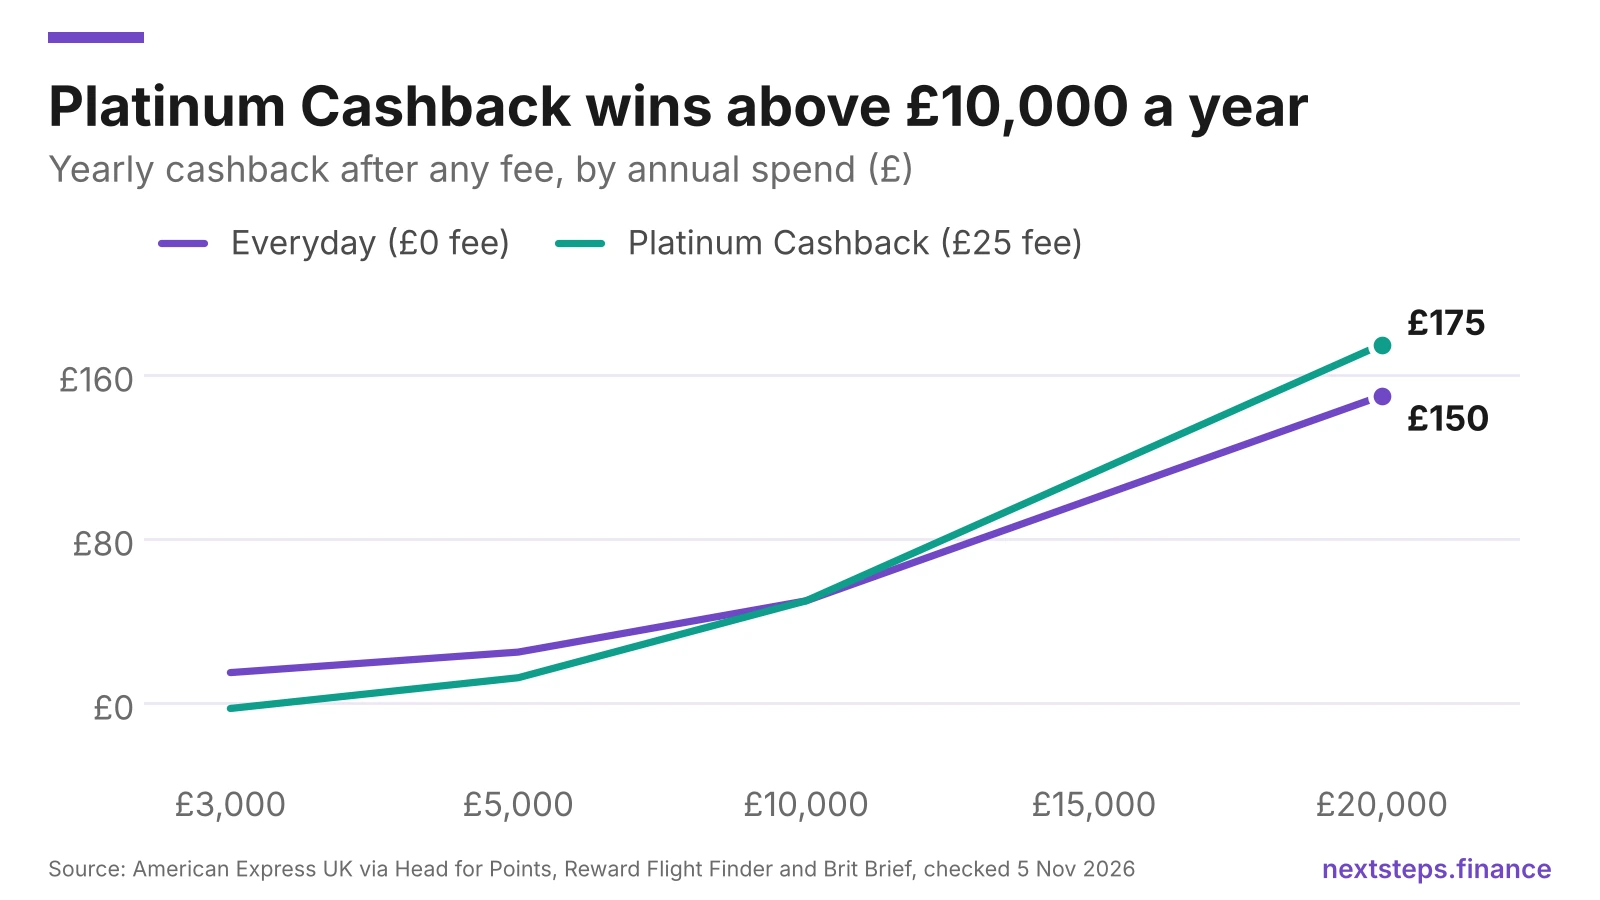
- Break-even: £10,000 a year. Above that, Platinum Cashback pays more after its fee.
Cashback Everyday vs Platinum Cashback side by side
| Platinum Cashback Everyday | Platinum Cashback | |
|---|---|---|
| Annual fee | £0 | £25 |
| Representative APR | 29.1% variable | 34.6% variable (includes fee) |
| Purchase rate | 29.1% variable | 29.1% variable |
| Intro cashback | 2% for 12 months, max £200 | 5% for 3 months, max £125 |
| First £10,000 a year | 0.5% | 0.75% |
| Above £10,000 | 1% | 1.25% |
| Warehouse clubs | Standard tiers | 0.5% |
| Minimum annual spend | £3,000 | None stated |
| Minimum income | £15,000 | £20,000 |
| Paid | Annually | Annually |
Amex has recently renamed them the Amex Cashback Everyday Credit Card and the Amex Cashback Credit Card. Intro offers change often, so check the current terms on Amex's application page.
How much does each pay at your spending level?
Here's the yearly cashback after the intro period, net of any fee:
| Annual spend | Everyday | Platinum Cashback (after £25) | Better card |
|---|---|---|---|
| £2,500 | £0 | -£6.25 | Neither |
| £3,000 | £15 | -£2.50 | Everyday |
| £5,000 | £25 | £12.50 | Everyday |
| £10,000 | £50 | £50 | Equal |
| £15,000 | £100 | £112.50 | Platinum Cashback |
| £20,000 | £150 | £175 | Platinum Cashback |
| £30,000 | £250 | £300 | Platinum Cashback |
Put in your own monthly spending:
Calculator
Which Amex cashback card pays you more?
- Monthly card spending£900
- Cashback rate on your first £10,000 (%)0.75%
- Annual fee£25
Cashback a year£56
Per month£6.75
After the yearly fee of£25
Over 5 years£280
Set up for Platinum Cashback (0.75%, £25 fee). For Everyday, change the rate to 0.5 and the fee to 0. Spending above £10,000 a year earns 1.25% on Platinum Cashback and 1% on Everyday, so heavy spenders earn more than shown.
Take Action: Check your last 12 months of card and debit spending that could go on an Amex. If it's comfortably above £10,000, choose Platinum Cashback.
Which is better in year one?
Everyday, in most cases. Its 2% intro rate runs for 12 months and pays up to £200, which you'd reach at £10,000 of spending. Platinum Cashback's 5% intro rate pays up to £125 in three months, then you're on the standard 0.75% and 1.25% rates, minus the £25 fee. Unless you spend very heavily in year one, Everyday pays more in the first year, and Platinum Cashback only pulls ahead from year two.
Can you switch between them?
You can usually ask Amex to move between the two cards, but you won't get a second intro bonus. Because of the 24-month rule, you also can't collect both intro offers back to back. So pick based on your expected spending before you apply.
Cashback or points?
If you'd redeem for flights, points can be worth more than 1.25%. Amex Gold converts to Avios at 1:1, and through a referral it's free in year one with 35,000 points plus a £100 Selfridges card until 12 January 2027. Our cashback vs Avios guide helps you decide, and our Amex Gold review covers the offer. You can apply for Amex Gold with our referral link (Representative 85.8% APR variable, credit subject to status).
For each cashback card on its own, read our Cashback Everyday review and Platinum Cashback review.
Things to watch out for on both
- Interest at 29.1% variable cancels out cashback quickly.
- Annual payment. Closing either card before your anniversary may lose that year's cashback.
- Amex acceptance. Keep a Visa or Mastercard as backup.
- 2.99% foreign spending fee on both cards.
FAQ
Which Amex cashback card is best?
It depends on your spending. The free Platinum Cashback Everyday is best if you spend between £3,000 and £10,000 a year. The £25 Platinum Cashback card is best if you spend more than £10,000 a year, because its higher rates outweigh the fee.
At what spend is Amex Platinum Cashback worth the fee?
At £10,000 a year, both cards pay £50 after fees. Above that, Platinum Cashback pays more. At £20,000 a year, it returns £175 after its £25 fee, compared with £150 on the free Cashback Everyday card.
What are the Amex cashback card intro offers?
Cashback Everyday pays 2% cashback for your first 12 months, up to £200. Platinum Cashback pays 5% for your first three months, up to £125. Both offers are for new cardmembers who haven't held a personal Amex card in the previous 24 months.
Is there a minimum spend on the Amex cashback cards?
Platinum Cashback Everyday pays no cashback in a year with less than £3,000 of spending. The fee-paying Platinum Cashback card doesn't state a minimum, but at low spending levels its £25 fee can exceed the cashback you earn.
Can I have both Amex cashback cards?
Holding both rarely makes sense, because they pay similar rates and the intro offer is limited to new cardmembers who haven't held a personal Amex in 24 months. Choose the card that suits your expected annual spending instead.
The bottom line
The decision is simple: under £10,000 a year, choose the free Cashback Everyday (as long as you spend at least £3,000); over £10,000, choose Platinum Cashback. If you'd use points for travel, Amex Gold may beat both in year one.
Apply for Amex Gold with our referral link if you'd rather earn points. Representative 85.8% APR variable. Credit is subject to status.
Found this useful? Add Next Steps Finance as a preferred source and Google will show you more of our guides in search and AI answers.