Looking for a UK bank account, no credit history to show? It's easier than most newcomers expect. A current account isn't credit, so banks mainly check who you are and where you live, not your borrowing record. The hard part is usually proof of address, not your credit file.
This guide covers which accounts accept people with a thin or empty file, what each one asks for, your legal right to a basic bank account, and how your first account starts building a UK credit history. Every rule below was checked on the provider's own site, MoneyHelper or GOV.UK on 14 November 2026.
Key takeaways
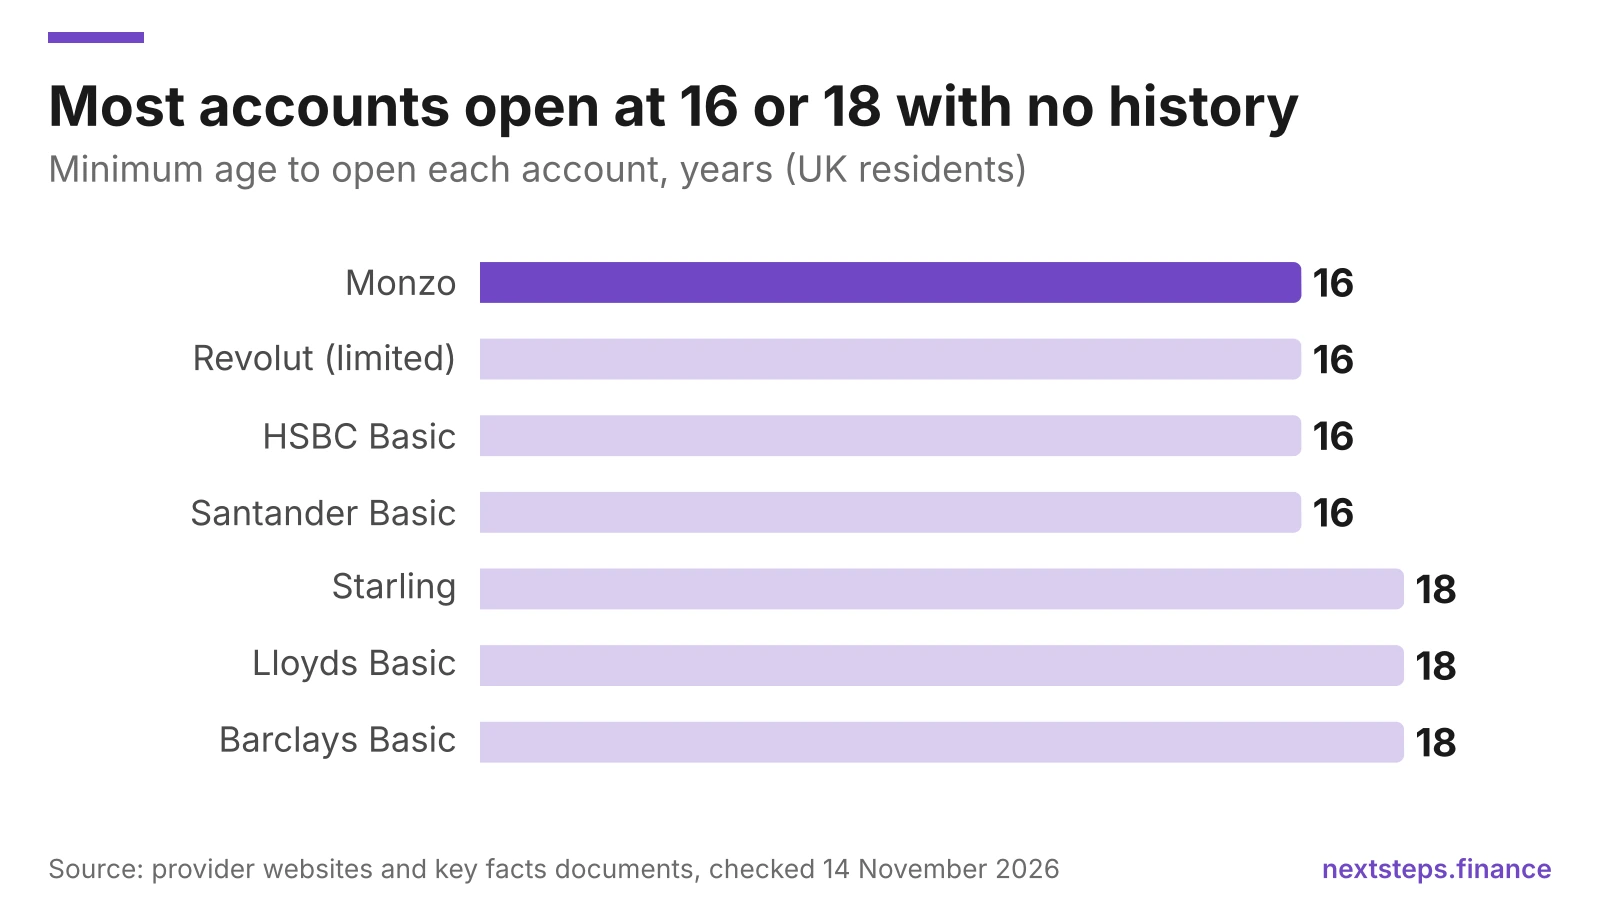
Monzo runs a soft search when you apply, which Monzo says "won't affect your credit score"; you need to be 16+ and live in the UK full time.
Nine banking groups must offer a fee-free basic account under the Payment Accounts Regulations 2015, and must decide within 10 business days.
7,039,100 basic bank accounts were open at those nine banks on 30 June 2024, according to HM Treasury's latest report.
Basic accounts have no overdraft and no fee for failed payments, so you can't run up bank charges while you build a history.
UK bank deposits are protected up to £120,000 per person, per banking group, by the FSCS since 1 December 2025. E-money accounts such as Wise are not.
Source: provider websites and key facts documents, checked 14 November 2026
Can you open a UK bank account with no credit history?
Yes. A UK bank account with no credit history is normal for new arrivals, students and anyone who has never borrowed. Banks have to confirm your identity and address to meet money laundering rules, but an empty credit file on its own isn't a reason to refuse a basic account.
What a bank checks depends on the account:
What they check
Why
Can no history stop you?
Photo ID (passport, driving licence or national ID card)
Proves who you are
No, but you need valid ID
UK address
Money laundering and fraud rules
Sometimes, if you can't prove it
Right to live in the UK
Immigration rules
Yes, if you aren't legally resident
Credit search
Mainly for overdrafts
Can limit you to an account without an overdraft
If a bank turns you down for its standard account, ask for its basic account instead. Citizens Advice says you "should still be able to get a basic account" even with previous bad debts or county court judgments (Citizens Advice).
Take Action: apply for the account you want first, and if you're refused, ask the same bank for its basic account in writing.
Which banks don't need a credit history?
App banks are usually the quickest UK bank account with no credit history, because they verify you with photo ID and a selfie video rather than paperwork. The high street banks also accept you, but often through their basic account.
Monzo asks you to be "at least 16" and to "live in the UK full time, with the right to reside here", with a passport, driving licence ("provisional is fine") or national ID card (Monzo help). Monzo says its soft search "won't affect your credit score" (Monzo).
Starling says "the initial checks leave a soft footprint on your credit file", while "the overdraft check leaves a hard credit check footprint" (Starling). So skip the overdraft at first if you want to keep your file clean. Our Monzo vs Starling vs Revolut comparison goes through the three apps feature by feature.
Revolut now has a UK banking licence: Revolut Bank UK Ltd left its mobilisation phase on 11 March 2026, and eligible deposits are FSCS protected. Revolut said existing customers would move across in phased batches, so check which entity holds your account in the app (Revolut).
Wise isn't a bank. It gives you a UK sort code and account number that accept Faster Payments, Bacs and CHAPS, which is handy for moving money from abroad, but your balance isn't covered by the FSCS (Wise). For a closer look, see our Revolut vs Wise comparison.
Through our Monzo link, a new customer aged 18+ with no Monzo account gets £10 and a free month of Monzo Extra after downloading the app, applying, adding money and making a card payment (no minimum) within 30 days. Monzo's referral terms (version 1.0) have no end date but can change at any time.
What is a basic bank account and who can get one?
A basic bank account is a fee-free account for people who can't get a standard current account. You get a debit card, can have wages and benefits paid in, and can pay Direct Debits and standing orders, but there's no overdraft (MoneyHelper).
Under regulation 23 of the Payment Accounts Regulations 2015, you qualify if you're "legally resident in the United Kingdom" and either have no other UK current account or aren't eligible for the bank's other accounts. People with no fixed address and asylum seekers are covered.
HM Treasury names nine banking groups that must offer one: Barclays UK, Co-operative Bank, HSBC UK, Lloyds Banking Group, Nationwide, NatWest Group, Santander UK, TSB and Virgin Money UK (HM Treasury). MoneyHelper lists the products by name:
Bank
Basic account name
Barclays
Basic Current Account
Lloyds, Halifax, Bank of Scotland
Basic Account
HSBC
Basic Bank Account
NatWest, RBS, Ulster Bank
Foundation Account
Santander
Basic Current Account
Nationwide
FlexBasic
Co-operative Bank
Cashminder
TSB
Cash Account
Virgin Money
M Account
The rules that matter most if you're starting out:
The bank must decide within 10 business days of a completed application (regulation 24).
A refusal must be explained in writing, free, with details of the Financial Ombudsman (regulation 25).
No overdrafts are allowed (regulation 19), and no fee for a payment that fails because you don't have enough money (regulation 20).
You don't need to pass a credit check. MoneyHelper says a bank can refuse if you won't agree to a check, not because of what it shows.
Some accounts have a small buffer that MoneyHelper says is "typically £10". The company you were paying can still charge you for a missed payment, so keep an eye on your balance.
What ID do you need to open a UK bank account?
Most banks want one photo ID and evidence of your UK address. For a UK bank account with no credit history, the address is often the sticking point, because new arrivals don't yet have bills in their own name.
Monzo accepts these if it asks for proof of address (Monzo help):
a utility bill, government letter or bank statement from the last 3 months
a council tax bill for the current year
a valid UK tenancy agreement
a UK driving licence, if you didn't use it as your photo ID
HSBC says it accepts "non-standard ID documents" for its Basic Bank Account (HSBC). If you have no standard documents, Citizens Advice says banks should accept a letter from "a responsible person who knows you", such as a GP, teacher or social worker. Barclays asks for a UK mobile number and home address for its basic account (Barclays).
Take Action: ask your employer, university or letting agent for a letter confirming your UK address in your first week. It opens more doors than any other single document.
Does opening a bank account affect your credit score?
Opening a current account usually has little effect on your score. Whether the bank uses a hard or soft search "depends on the provider", says ClearScore, and a hard search is more likely if the account comes with an overdraft.
Monzo says its opening search is soft, and Lloyds says the same for its Basic Account: a soft search that "won't impact your credit score" (Lloyds). Lenders can't see soft searches, so they don't count against you when you later apply for credit.
The bigger effect is positive. Monzo says that when you open a current account it has to tell its credit reference agency, so the account appears on your file. Experian says "having a bank account and managing it well shows companies you're financially responsible" (Experian), though a new account can dip your score briefly before it helps.
How do you build a UK credit history once you have an account?
Your first bank account starts your UK credit file, and a few simple steps build it faster. Most of them cost nothing.
Pay your salary into one main account and keep it in credit. A steady record of income and bills is the base of your file.
Register to vote if you're eligible. In England and Northern Ireland, British, Irish and qualifying Commonwealth citizens (including South Africans) with permission to stay can register from 16, as can citizens of Denmark, Luxembourg, Poland, Portugal and Spain (GOV.UK). Scotland and Wales allow anyone with permission to stay. Experian says lenders use this to confirm your name and address.
Put a bill in your name, such as a mobile contract, broadband or energy.
Check your file for free with the credit reference agencies after a few months to make sure your address is right.
Hold off on credit cards until you've had a few months of steady history, so a refusal doesn't leave a hard search.
Once you're paid into a UK account, the next step is a budget for your first few months. If you'd rather not build one from scratch:
Which account suits you if you've just moved to the UK?
It depends on whether you need speed, a branch or a way to bring money from abroad. Many newcomers use two accounts: an app bank to get paid quickly, and a high street bank later for mortgages and branch services.
Through our Lloyds link, someone with no existing Lloyds current account, savings, credit card, loan or mortgage gets £30 within 35 calendar days of opening a new current account in their sole name through the app. Student, Under 19s, Smart Start, Money Smart and Expresscash accounts don't count, and Lloyds can withdraw the offer without notice (Lloyds). Lloyds' standard accounts may involve different checks from its Basic Account, so read the eligibility screen before you apply.
The downsides are real: app banks rarely have branches, Wise balances aren't FSCS protected, and a basic account won't give you an overdraft for emergencies. If you're moving from South Africa, our money checklist for moving to the UK from South Africa covers the rest of your first 90 days, our best bank accounts guide compares the full market, and once you have history, our bank switching offers page lists the current cash bonuses.
Frequently asked questions
Can I open a UK bank account without proof of address?
Often, yes. Monzo only asks for proof of address in some cases, and HSBC's Basic Bank Account accepts non-standard ID. Citizens Advice says banks should accept a letter from someone who knows you, such as a GP or social worker, if you lack the usual documents. A tenancy agreement is accepted by Monzo too.
Which UK bank accounts don't do a credit check?
Most UK banks run some check, but many use a soft search that lenders can't see and that doesn't affect your score. Monzo, Starling (without an overdraft), HSBC's Basic Bank Account and Lloyds' Basic Account all say their opening searches are soft, as checked on 14 November 2026.
Can a bank refuse me a basic bank account?
Only in limited cases. Under the Payment Accounts Regulations 2015, a bank must refuse if opening the account would break money laundering, fraud or immigration law, and may refuse if you've been abusive to staff. It must give the reason in writing, free, and tell you about the Financial Ombudsman.
Does a bank account help build credit in the UK?
Yes. Banks such as Monzo report current accounts to credit reference agencies, so your account appears on your credit file. Experian says managing a bank account well shows lenders you're financially responsible. Registering to vote, where eligible, and keeping your address up to date help too.
How long does it take to open a basic bank account?
The bank must make a decision no later than 10 business days after you send a completed application, under regulation 24 of the Payment Accounts Regulations 2015. App-based applications are often faster, and most app banks give you account details within minutes of passing their ID checks.
The bottom line
A UK bank account with no credit history is well within reach. App banks like Monzo and Starling open with a soft search, and if a high street bank says no to its standard account, the law gives you a right to a fee-free basic account if you're legally resident. Get one account open in your first week, get paid into it, register to vote where you can, and your UK credit file starts building from there.
Found this useful? Add Next Steps Finance as a preferred source and Google will show you more of our guides in search and AI answers.