Revolut's savings account is easy to use and pays interest every day, but the rate you get depends on which Revolut plan you pay for. On the free plan it pays 2.90% AER, well below the best easy access accounts, which pay up to 5.00% this week.
I've checked Revolut's own savings summary box and pricing page today, and compared them with the top easy access deals on Moneyfacts. Here's what you actually earn, how safe your money is, and when it's worth using.
Key takeaways
- Rates by plan (AER, variable): Standard and Plus 2.90%, Premium 3.25%, Metal 3.40%, Ultra 4.00% up to £200,000 and 3.51% above that (Revolut summary box).
- Interest is calculated daily and paid gross the next calendar day. There's no minimum deposit and no withdrawal limit.
- Your money is held with ClearBank, and protected by the FSCS up to £120,000 per person, per bank.
- The best easy access rate on 30 October 2026 is 5.00% AER (LemFi, including a six-month bonus), and Oxbury Bank pays 4.57% with no bonus (Moneyfacts).
- A paid plan only pays for itself through savings with large balances: roughly £27,000 for Premium, £36,000 for Metal and £60,000 for Ultra.
What interest rate does Revolut pay on savings?
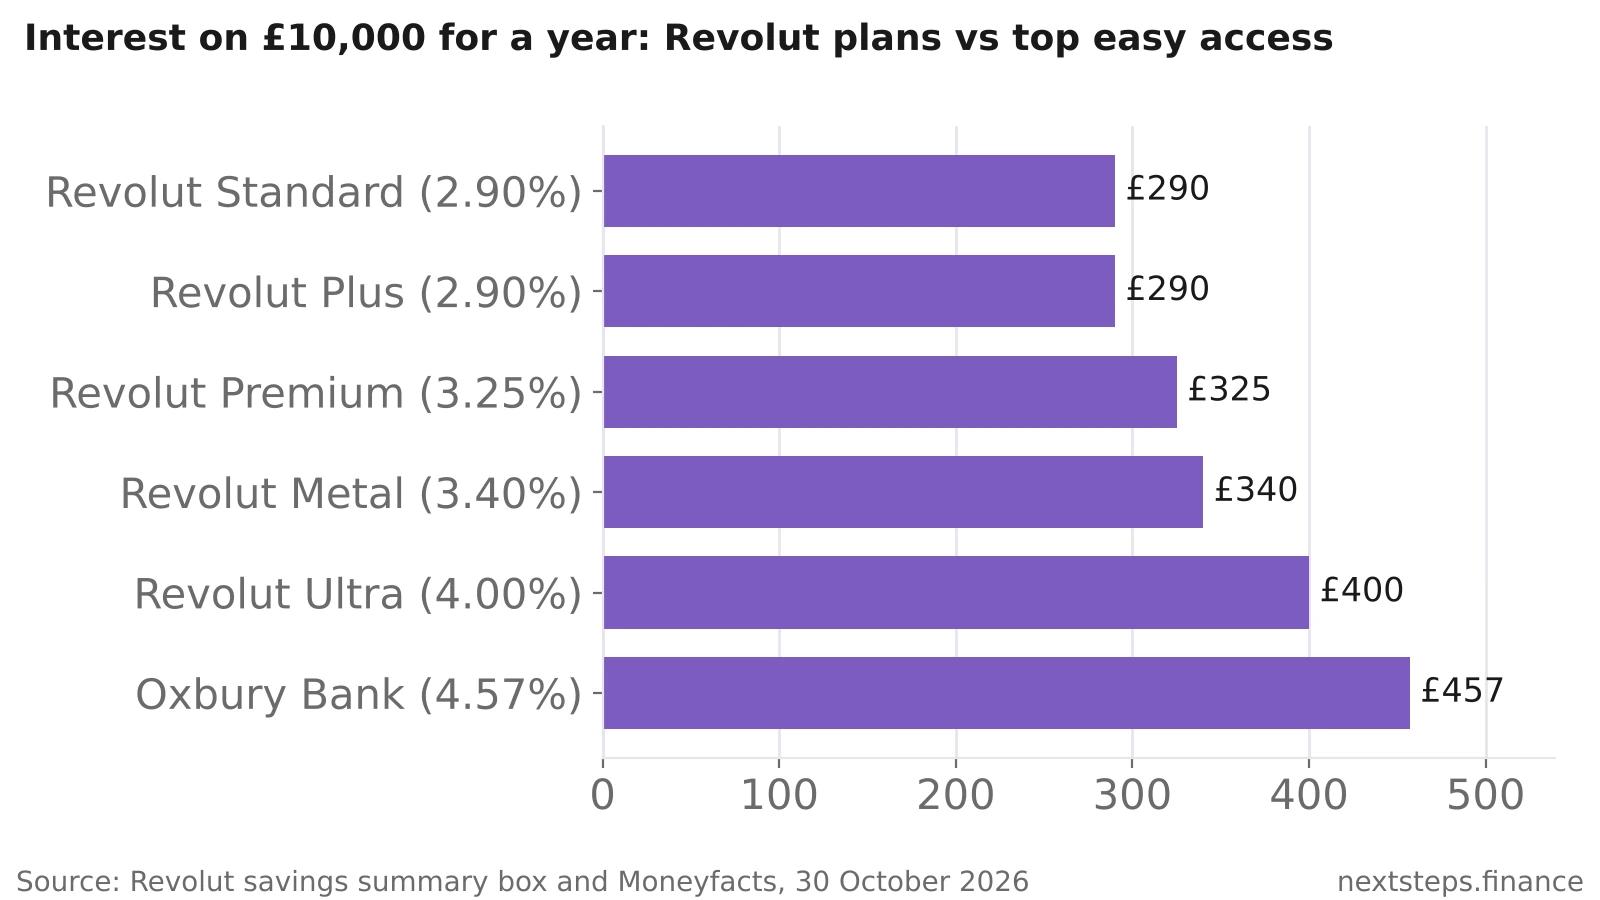
Revolut pays between 2.90% and 4.00% AER variable on its Instant Access Savings, depending on your plan. These are the rates in Revolut's summary box, which applies to all accounts from 20 May 2026 and matches its UK pricing page today.
| Revolut plan | Listed monthly price | Savings rate (AER, variable) | Interest on £10,000 a year |
|---|---|---|---|
| Standard | Free | 2.90% | £290 |
| Plus | £3.99 | 2.90% | £290 |
| Premium | £7.99 | 3.25% | £325 |
| Metal | £14.99 | 3.40% | £340 |
| Ultra | £55 | 4.00% up to £200,000, 3.51% above | £400 |
The plan prices are the ones on Revolut's pricing page on 30 October 2026. Revolut's paid plans are 12-month plans that you can pay for monthly or annually, and some comparison sites list higher monthly figures (for example £16.99 for Metal and £60 for Ultra), so check the exact price in the app before you upgrade.
The rate is variable. Revolut can change it up or down, and it promises at least 14 days' notice of a cut. With the Bank of England's next rate decision due on 5 November 2026, and Bank Rate held at 3.75% at the September meeting on a 6-3 vote (MTS Insights summary), easy access rates across the market could move in either direction.
Take Action: Check which plan you're on in the Revolut app (Profile, then Plan). The rate shown in your savings account is the one you're actually getting.
How does the Revolut savings account work?
You open it in the Revolut app in a couple of minutes, move money in from your Revolut balance, and take it back out whenever you like. It's a genuinely instant access account.
The key terms from Revolut's summary box:
- Interest is calculated daily on your total end-of-day balance across your Instant Access Savings accounts, and ClearBank pays it the next calendar day.
- Interest is paid gross, meaning no tax is taken off. You're responsible for any tax due (see below).
- No minimum balance. The maximum across all your Instant Access Savings is £5,000,000.
- No withdrawal restrictions. Money moved back is usually available to spend on your Revolut account immediately.
- Eligibility: you must be 18 or over, a UK tax resident, a Revolut personal account customer who has passed its checks, and not a US person.
Daily interest is nice to see, but it doesn't make you richer on its own. The AER already includes the effect of compounding, so 2.90% paid daily is still 2.90% a year.
Is the Revolut savings account safe and FSCS protected?
Yes. Revolut's summary box says money in Instant Access Savings is "deposited on your behalf directly within your Financial Services Compensation Scheme (FSCS) protected account held with ClearBank". Compensation is limited to £120,000 per person, per bank.
Two details matter here:
- The protection is with ClearBank, not Revolut. Revolut introduces you to ClearBank and runs the account in its app. If you already hold money with ClearBank through another provider, the £120,000 limit is shared.
- Money left in your main Revolut balance is a separate pot. Moving it into savings is what puts it into the ClearBank account described above.
If you hold more than £120,000 in cash, spread it across banks with separate banking licences so all of it is covered.
Is a paid Revolut plan worth it just for the savings rate?
Usually not. The extra interest from a higher plan only covers the plan fee if you hold a large balance in savings.
Here's the maths using Revolut's listed prices. Premium pays 0.35 percentage points more than Standard and costs about £96 a year, so you need roughly £27,400 in savings to break even. Metal pays 0.50 points more and costs about £180 a year, so you need about £36,000. Ultra pays 1.10 points more and costs £660 a year, so you need around £60,000 saved before the extra interest covers the fee.
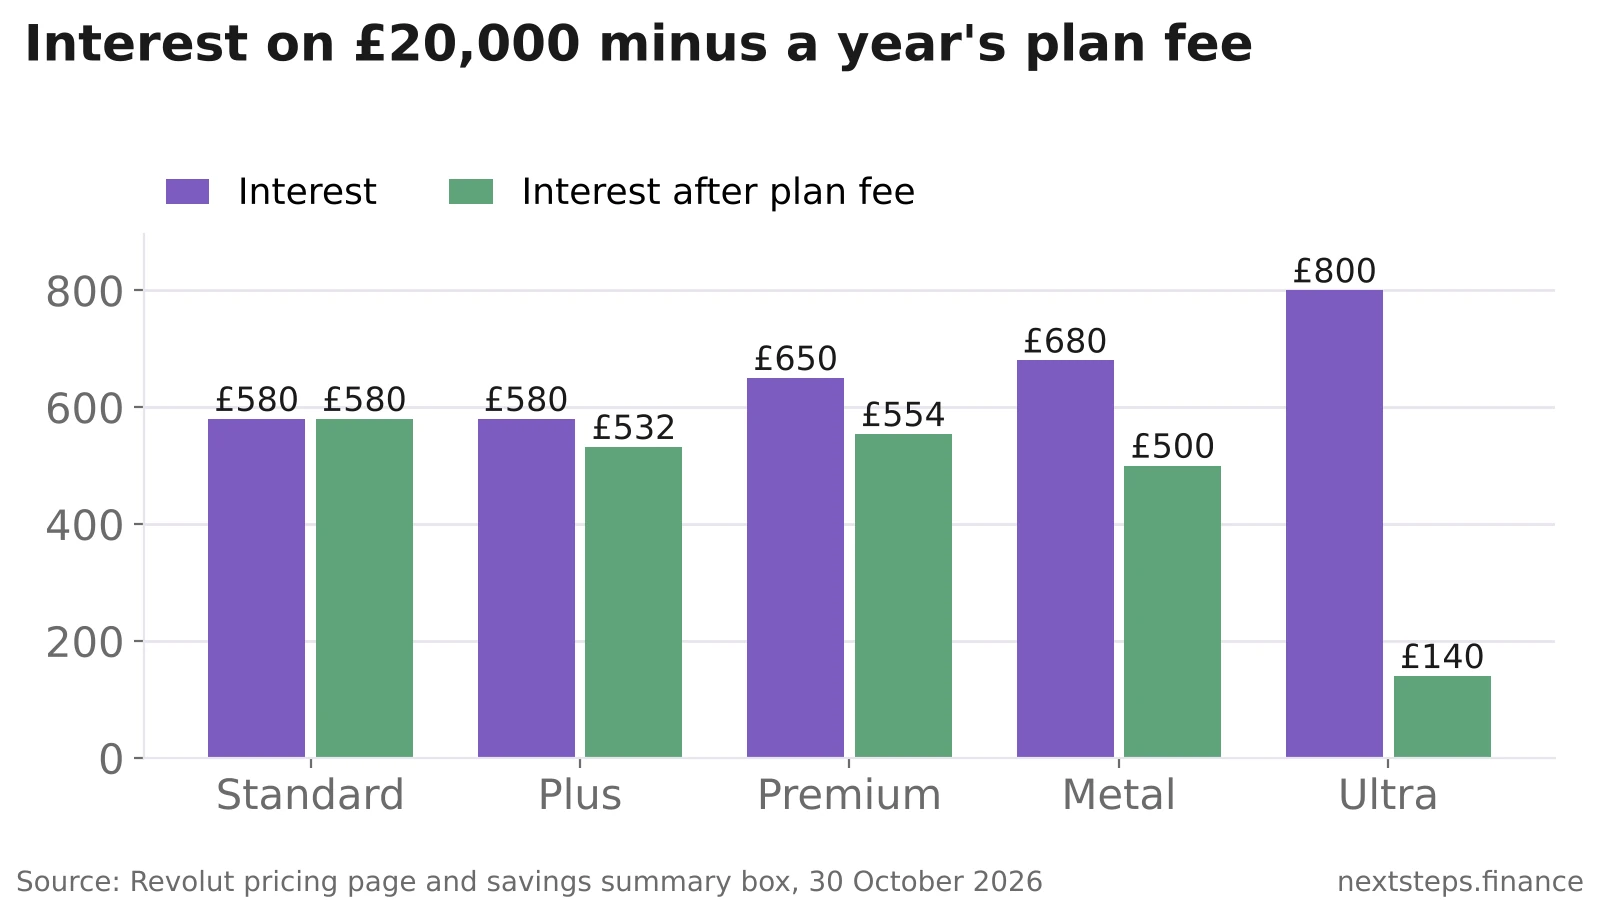
On £20,000, the free Standard plan leaves you best off once fees are counted. A paid plan can still make sense if you'd use its other perks, such as travel insurance on Metal or the bundled subscriptions on Premium. I've weighed those up in Revolut plans compared. Just don't upgrade for the savings rate alone.
Take Action: If you're on a paid plan, multiply your savings balance by the rate difference and compare it with what you pay. If the fee is bigger, the plan is earning its keep elsewhere or not at all.
How does Revolut compare with the best easy access accounts?
Revolut's free rate is well below the best buys. On 30 October 2026, Moneyfacts lists these at the top of the easy access market:
| Account | Rate (AER) | Catch |
|---|---|---|
| LemFi | 5.00% | Includes a 1.89% bonus for six months |
| Oxbury Bank | 4.57% | No bonus |
| Zopa | 4.56% | Includes a 1.05% bonus for 12 months |
| Revolut Ultra | 4.00% | £55 a month plan |
| Revolut Standard | 2.90% | None, but a low rate |
Bonus rates drop once the bonus ends, so the headline figure isn't what you'll earn in year two. Our guide to whether to fix your savings shows how much more fixed accounts are paying if you can lock money away.
Where Revolut does well is convenience. If you already use Revolut as your everyday account, moving spare cash into savings takes a tap, and it's back in your spending balance instantly. That makes it a reasonable home for a small buffer you dip into often. For a bigger emergency fund you won't touch for months, a higher-paying account elsewhere earns noticeably more.
Do you pay tax on Revolut savings interest?
You may do. Revolut pays interest gross, and it's taxable like interest from any bank account. Most people won't pay tax because of the Personal Savings Allowance.
According to GOV.UK, you can earn £1,000 of interest tax-free as a basic-rate taxpayer, £500 as a higher-rate taxpayer and £0 as an additional-rate taxpayer. If your other income is under £17,570, the starting rate for savings can make up to £5,000 more interest tax-free.
At 2.90%, a basic-rate taxpayer could hold about £34,000 before going over £1,000 of interest. A higher-rate taxpayer reaches the £500 limit at around £17,000. Above that, HMRC usually collects the tax through your tax code, or through Self Assessment if your interest is over £10,000.
The tax rates on savings interest are going up from April 2027, which makes ISAs more valuable for bigger balances. Our guide to the savings tax rise explains who's affected.
Who is the Revolut savings account good for?
It may suit you if you already bank with Revolut and want somewhere easy to park a modest amount, or if you pay for Premium or Metal anyway for the other perks.
It's less suited to:
- Savers chasing the top rate. You'll earn 1.5 to 2 percentage points more in the best easy access accounts.
- Higher-rate taxpayers with larger balances. A cash ISA keeps the interest tax-free.
- Anyone who'd upgrade just for the rate. The fee usually costs more than the extra interest.
If you're new to Revolut, you can sign up to Revolut and open the savings account from the app once your account is verified. Any welcome reward depends on Revolut's current promotion, so check the terms shown when you join. To see how much you can realistically put aside each month, try our free UK Budget Planner, and if you're torn between apps, read Monzo vs Revolut.
FAQ
Is Revolut savings account good?
Revolut's savings account is good for convenience but not for rate. It pays 2.90% AER variable on the free plan, with daily interest and instant withdrawals. The best easy access accounts paid 4.57% to 5.00% on 30 October 2026, so larger balances usually earn more elsewhere.
Is my money safe in Revolut savings?
Yes, money in Revolut's Instant Access Savings is held in an FSCS-protected account with ClearBank. Compensation covers up to £120,000 per person, per bank. If you also hold money with ClearBank through another provider, that £120,000 limit is shared between them.
How much interest will I get on £10,000 with Revolut?
On £10,000 held for a year, Revolut pays about £290 on Standard or Plus, £325 on Premium, £340 on Metal and £400 on Ultra, based on its October 2026 rates. Rates are variable, so the amount changes if Revolut moves its rates during the year.
Does Revolut pay interest daily?
Yes. Revolut calculates interest every day on your end-of-day savings balance and ClearBank pays it the next calendar day, without deducting tax. Daily payment doesn't increase the yearly return beyond the AER, which already includes compounding.
Can I withdraw money from Revolut savings at any time?
Yes. Revolut's Instant Access Savings has no withdrawal limits or notice periods. You move money back to your Revolut balance in the app, and it's usually available to spend immediately. There's no minimum balance either.
Do I have to pay tax on Revolut savings interest?
Only if your total interest from all accounts is above your allowances. Basic-rate taxpayers get £1,000 tax-free, higher-rate £500 and additional-rate £0. Revolut pays interest gross, and HMRC collects any tax due through your tax code or Self Assessment.
The bottom line
Revolut's savings account is quick, flexible and FSCS protected through ClearBank, and it pays interest every day. But 2.90% on the free plan is a long way behind the market leaders, and paid plans rarely earn back their fees through interest alone.
Use it for a small, everyday buffer if you already bank with Revolut. For a larger pot, compare the best easy access and fixed rates first, and keep the bulk of it wherever it earns the most.