A 50k salary budget in the UK starts with the roughly £3,147 that reaches your account each month once Income Tax, National Insurance and a 5% pension have come off. That's comfortably above the typical full-time salary, so most people on £50,000 can save a real amount each month. The catch is that you're right at the edge of the 40% tax band, so the next pay rise is worth less than you'd expect. This guide shows the 2026/27 numbers, three worked monthly budgets and a savings plan.
Foundations
50k Salary Budget UK: How to Budget on £50,000
50k salary budget UK: £50,000 is about £3,147 a month after tax, NI and pension in 2026/27. Three worked budgets and how much to save.
In this article
- 01Key takeaways
- 02How much is £50,000 a year after tax in the UK?
- 03Is £50k a good salary in the UK?
- 04What does a monthly budget on £50k look like?
- 05What happens if my £50k salary goes over £50,270?
- 06How much should I save on a £50,000 salary?
- 07What's the easiest way to stick to a £50k budget?
- 08FAQ
- 09The bottom line
Key takeaways
- Take-home pay on £50,000 is about £3,293 a month in England, Wales and Northern Ireland in 2026/27, or about £3,147 after a 5% auto-enrolment pension.
- Tax and NI cost £10,480 a year: £7,486 Income Tax and £2,994 National Insurance. In Scotland you pay about £1,496 more Income Tax.
- You're £270 below the higher-rate threshold of £50,270, which GOV.UK confirms stays frozen until 5 April 2031. Above it, you keep only 58p of each extra pound.
- Average UK rent of £1,411 a month (ONS, October 2026) takes 45% of take-home pay, against 27% for the Wales average of £849.
- Your pension gets about £292 a month once your employer's 3% is added to your own 5%.
To plan your own £50k budget month by month, the UK Budget Planner starts from your real take-home pay and tracks bills, savings and sinking funds across the year.
How much is £50,000 a year after tax in the UK?
£50,000 a year is about £39,520 after tax and National Insurance, or £3,293 a month, in England, Wales and Northern Ireland in 2026/27. After a standard 5% workplace pension it's about £37,769 a year, or £3,147 a month.
The working uses the GOV.UK rates and thresholds for employers 2026 to 2027: a £12,570 Personal Allowance, 20% basic rate on the next £37,700, and employee National Insurance of 8% between £12,570 and £50,270.
| Per year | Per month | |
|---|---|---|
| Gross salary | £50,000 | £4,167 |
| Income Tax (20% on £37,430 above the Personal Allowance) | -£7,486 | -£624 |
| National Insurance (8% on £37,430) | -£2,994 | -£250 |
| Take-home before pension | £39,520 | £3,293 |
| Pension: 5% of earnings between £6,240 and £50,270, after 20% tax relief | -£1,750 | -£146 |
| Take-home after pension | £37,769 | £3,147 |
The pension line assumes the auto-enrolment minimum. GOV.UK's workplace pensions guide says you pay at least 5% and your employer at least 3% of qualifying earnings between £6,240 and £50,270 a year. On £50,000 that's £2,188 a year from you (£1,750 after tax relief) and £1,313 from your employer. Some schemes use your full salary instead, so check your payslip. Our UK income tax guide explains the bands in more detail.
Student loans and Scotland
Two things can change your number:
- Student loan: you repay 9% of earnings above your plan's threshold. On £50,000 that's about £155 a month on Plan 2 (threshold £29,385), £173 on Plan 1 (£26,900), £122 on Plan 4 (£33,795) and £187.50 on Plan 5 (£25,000). A postgraduate loan adds 6% above £21,000, or £145 a month.
- Scotland: the Scottish Government's 2026 to 2027 bands put the 42% higher rate on income from £43,663. On £50,000 about £6,300 of your pay is taxed at 42%, so you pay around £8,982 Income Tax, £1,496 more than elsewhere. Take-home is about £3,169 a month before pension.
Our take-home pay calculator works this out for your exact salary, tax code and student loan plan.
Take Action: Check your last payslip. The net figure, not £50,000, is what every budget below is built on.
Is £50k a good salary in the UK?
Yes. £50,000 is well above the middle of the UK pay scale. The ONS reported on 22 October 2026 that median gross annual earnings for full-time employees who'd been in their job for at least a year were £40,911 in April 2026, up 4.5%. So £50,000 is about 22% more than the typical full-time salary.
The rise from £40k is smaller than it looks. Compared with our £40k salary budget, the extra £10,000 adds about £6,800 a year, or £567 a month, after tax, NI and the extra pension.
Rent decides how comfortable £50k feels. The ONS's latest rent figures, published 18 November 2026, put average private rent at £1,411 a month across the UK in October, up 3.8% in a year. That's £1,472 in England and £2,350 in London, against £849 in Wales, £1,015 in Scotland and £876 in Northern Ireland (August).
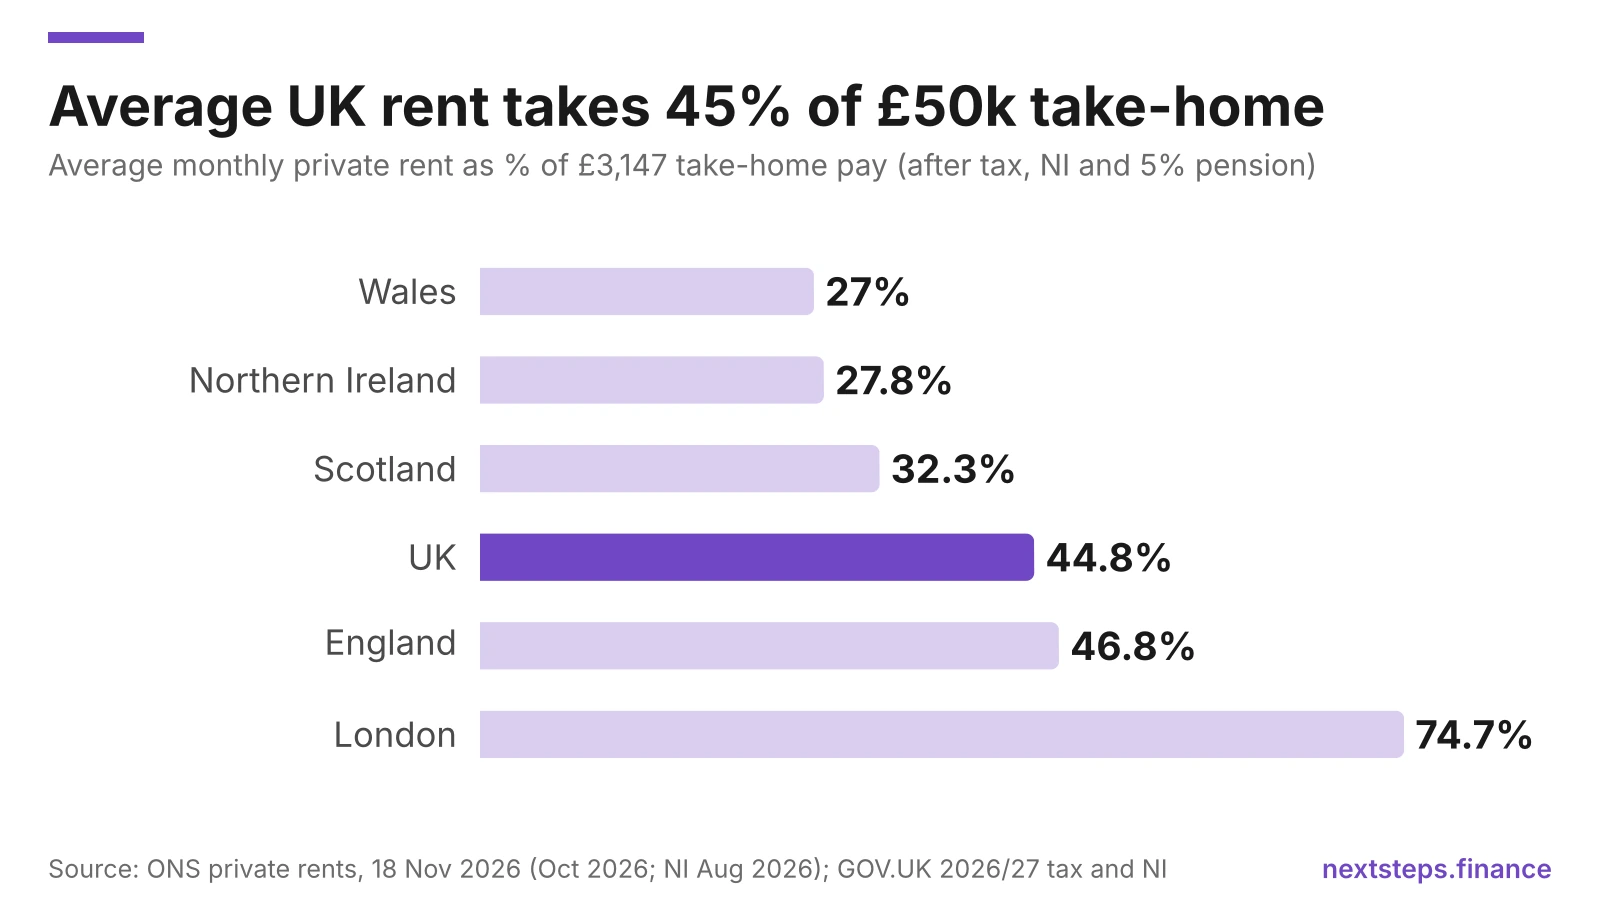
Outside London, £50,000 lets you rent a one-bed alone and still save well. In London, the average rent would take about three-quarters of take-home pay, so sharing or a cheaper area is still common even on this salary.
What does a monthly budget on £50k look like?
A workable 50k salary budget for a single renter puts around 60% of take-home pay on essentials, under 20% on spending and 20% or more on savings. The examples below use £3,147 a month (after a 5% pension) and official figures where they exist.
Official figures used:
- Council tax: £1,868 average per dwelling in England for 2026-27 (MHCLG), or £117 a month with the 25% single person discount.
- Energy: £1,723 a year for a typical dual-fuel household under the price cap for 1 October to 31 December 2026, Ofgem confirmed, or about £144 a month. Ofgem announces the January to March 2027 cap on 25 November. Our guide to average household bills in the UK covers every bill.
- Food at home: £33.63 per person per week on food and non-alcoholic drinks in DEFRA's Family Food FYE 2025, about £146 a month.
Travel, phone, broadband, water and insurance vary too much to average, so those lines are examples. Swap in your own.
Budget 1: living alone, rent £1,200
| Category | Monthly | Share of £3,147 |
|---|---|---|
| Rent (one-bed flat) | £1,200 | 38% |
| Council tax (single person discount) | £117 | 4% |
| Energy | £144 | 5% |
| Food shopping | £146 | 5% |
| Travel (example) | £150 | 5% |
| Phone, broadband, water, insurance (example) | £120 | 4% |
| Essentials total | £1,877 | 60% |
| Savings and extra debt payments | £700 | 22% |
| Spending money (eating out, clothes, gifts, subscriptions) | £570 | 18% |
| Total | £3,147 | 100% |
That's close to the 50/30/20 rule, and it saves £8,400 a year on top of your pension.
Budget 2: living alone at the England average rent
At £1,472, the same essentials come to £2,149 (68%). That leaves £998: about £460 to save (15%) and £538 to spend (17%). It still works, but a rent rise or a big bill eats most of the month's saving, so an emergency fund matters more.
Budget 3: a couple sharing the UK average rent
If you live with a partner and split a £1,411 rent, your half is £706. Add half the full council tax (£78), half the energy (£72), your own £146 food shop, £150 travel and £70 of other bills, and your essentials come to £1,222 (39%). That leaves about £1,000 to save (32%) and £925 to spend (29%). Our guide to budgeting for couples covers fair ways to split bills when incomes differ.
Take Action: Copy the budget closest to your life into the free budget template and replace every line with figures from your last three bank statements. The UK budget calculator does the first pass for you.
What happens if my £50k salary goes over £50,270?
Any pay above £50,270 is taxed at 40% Income Tax plus 2% National Insurance, so you keep 58p of each extra pound instead of 72p. On £50,000 you have just £270 of room before that happens.
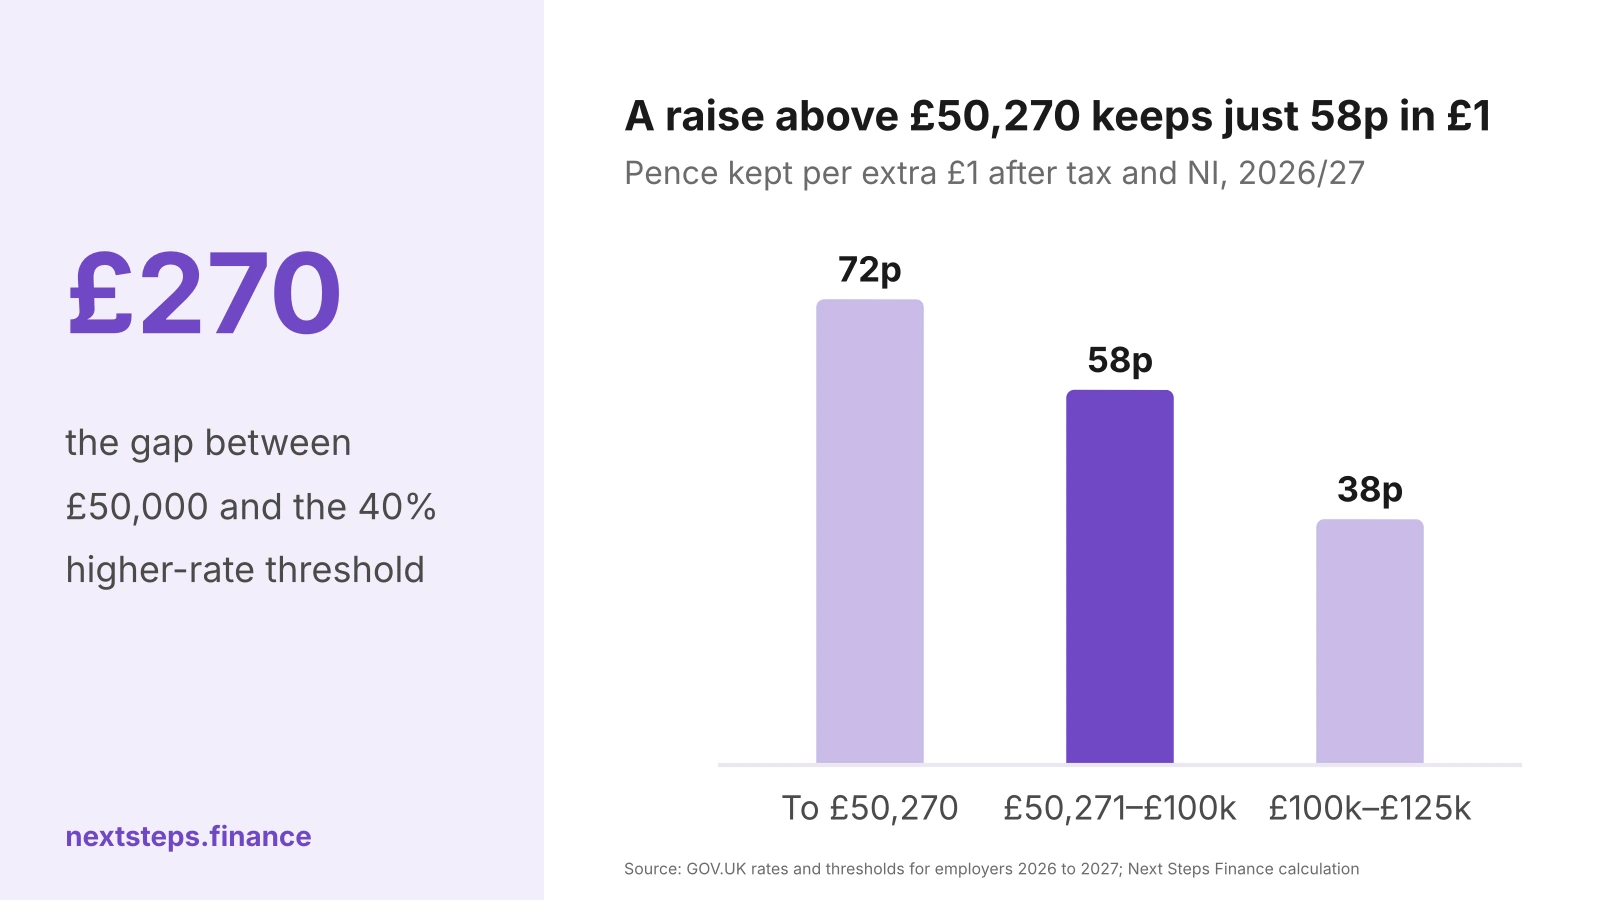
The government has frozen the Personal Allowance at £12,570 and the higher-rate threshold at £50,270 until 5 April 2031. So even a small pay rise pushes part of your salary into the 40% band, and more of it each year your pay goes up. In Scotland, £50,000 is already above the £43,663 higher-rate threshold, so a raise there keeps about 50p in the pound.
Two things to know:
- Pension contributions can keep you below £50,270. Paying more into your pension through salary sacrifice reduces your taxable pay. Our salary sacrifice calculator shows what each extra pound into your pension costs you in take-home pay.
- Child Benefit is safe for now. GOV.UK says the High Income Child Benefit Charge starts when adjusted net income goes over £60,000, at 1% of the benefit for every £200 above it, and takes it all back at £80,000. Our Child Benefit tax charge guide explains it.
Check where your own pay lands:
Calculator
Will your next pay rise be taxed at 40%?
- Your expected yearly salary£52,000
Your resultHigher rate, you keep 58p of each extra £1 after tax and NI
£12,571 or moreBasic rate, you keep 72p of each extra £1 after tax and NI
£50,271 or moreHigher rate, you keep 58p of each extra £1 after tax and NI
£60,001 or moreHigher rate, plus the Child Benefit charge if your household claims it
£100,001 or moreThe Personal Allowance taper, you keep 38p of each extra £1
2026/27 rates for England, Wales and Northern Ireland from GOV.UK, checked 22 November 2026. Scotland has different bands. The Child Benefit charge uses adjusted net income, which pension contributions reduce.
Take Action: If a pay rise takes you over £50,270, ask your employer whether you can put some of it into your pension through salary sacrifice.
How much should I save on a £50,000 salary?
On £50,000, saving £460 to £1,000 a month (roughly 15-32% of take-home pay) is realistic, depending mostly on rent. Build safety first, then save for goals.
- Emergency fund first. Three months of essentials from Budget 1 is about £5,600. At £700 a month that takes around eight months. Our emergency fund guide covers where to keep it.
- Clear expensive debt next. Paying off a credit card or overdraft usually beats any savings rate.
- Plan for yearly costs. Car insurance, Christmas and holidays go in sinking funds so they don't land on a credit card.
- Then invest for the long term. Once your cash buffer is in place, a stocks and shares ISA shelters your investments from tax on gains and dividends. Our best stocks and shares ISA guide compares the main options.
- Check your pension match. You and your employer already put about £292 a month into your pension. If your employer matches extra contributions, that's usually the best return on offer. Our employer pension guide explains how matching works.
Investing with InvestEngine
If you want to buy low-cost ETFs in an ISA, InvestEngine is one option. Under its incentive terms (referral programme V1.4), a new customer who joins through a referral link and funds an account with at least £100 gets a random welcome bonus between £20 and £200, and must stay invested for 12 months to keep it. The odds favour the bottom end: 75% of bonuses are £20 to £24, and only 2% are £150 to £200. Capital at risk - the value of investments can go down as well as up.
The downsides: the bonus is random and usually small, and on a DIY account you pick your own ETFs. A managed robo-adviser may suit you better if you'd rather not choose funds, and the big platforms offer similar ISAs without a bonus. Our InvestEngine review covers fees and features. Keep your emergency fund in cash, not investments.
What's the easiest way to stick to a £50k budget?
The easiest method is to split your pay on payday: one pot or account for bills, one for spending and one for savings. When each has its own balance, you can see what's left without tracking every coffee.
| Option | Who it may suit | Key point |
|---|---|---|
| Monzo pots | People who want bills, spending and savings in one app | £10 plus a free month of Monzo Extra for new customers via referral |
| Your existing bank + budget template | People happy with their bank | Free, but you move money yourself |
| A budgeting app (see our best budgeting apps) | People with accounts at several banks | Pulls everything into one view |
| UK Budget Planner | A full-year plan with sinking funds | Built for UK pay, tax and bills |
With Monzo, you can keep bills, spending and savings in separate pots inside one account. Under Monzo's referral terms, a UK resident aged 18+ with no Monzo account who joins through a referral link and, within 30 days, downloads the app, applies, adds money and makes a card payment (no minimum) gets £10 and a free month of Monzo Extra, which is a paid plan after that month. There's no end date at the moment, but Monzo can change the offer at any time. No account pays you to budget: the value is in keeping bill money out of sight.
On a bigger salary, lifestyle creep is the main risk. Move at least half of every pay rise into savings or your pension on the day it arrives, before you get used to spending it.
If you'd rather not build this yourself:
FAQ
How much is £50k a month after tax?
A £50,000 salary is about £3,293 a month after Income Tax and National Insurance in England, Wales and Northern Ireland in 2026/27. After a standard 5% workplace pension it's about £3,147 a month. In Scotland it's about £3,169 before pension. A student loan reduces it further, by about £155 a month on Plan 2 or £187.50 on Plan 5.
Do you pay 40% tax on £50,000?
No, not in England, Wales or Northern Ireland. The higher rate starts at £50,271, so all your taxable income on £50,000 is taxed at 20%. You're only £270 below the line, though. In Scotland, the 42% higher rate starts at £43,663, so about £6,300 of a £50,000 salary is taxed at 42% there.
Is £50k a good salary in the UK?
Yes. The ONS put median full-time earnings at £40,911 in April 2026, so £50,000 is about 22% above the typical full-time salary. It's comfortable for a single person in most of the UK, but average London rent of £2,350 would take about 75% of take-home pay, so many Londoners on £50k still share.
How much rent can I afford on £50k?
A common rule is to keep rent to about a third of take-home pay, which on £50,000 is roughly £1,050 a month. Up to £1,200 still leaves room to save around £700 a month if you live alone. At England's average rent of £1,472, saving falls to about £460 a month once council tax, energy and food are paid.
How much should I save on a £50k salary?
Aim to save 15-25% of take-home pay, or about £470-£790 a month on £50,000, once essentials are covered. Build an emergency fund of three months' essentials first, around £5,600 for a single renter paying £1,200. Your workplace pension adds about £292 a month on top, including your employer's 3% contribution.
The bottom line
A 50k salary budget in the UK works out at about £3,147 a month after tax, NI and a 5% pension. Keep rent to around 40% of that and you can cover essentials, save about £700 a month and still enjoy your money. Watch the £50,270 line: any rise above it is taxed at 42%, so salary sacrifice into your pension may be worth a look.
To turn these examples into your own plan, use the UK Budget Planner, or start with the free budget template. For the bigger picture, read our complete guide to budgeting in the UK or browse the budgeting hub.
Found this useful? Add Next Steps Finance as a preferred source and Google will show you more of our guides in search and AI answers.
Put this into practice
Build your budget in one sitting
The UK Budget Planner works out your take-home pay, splits it with the 50/30/20 rule, tracks spending through the year and forecasts five years ahead. Made for UK pay, tax and bills.